


London, 6 October 2026 — EBM Newsdesk Analysis — By Anthony Gill
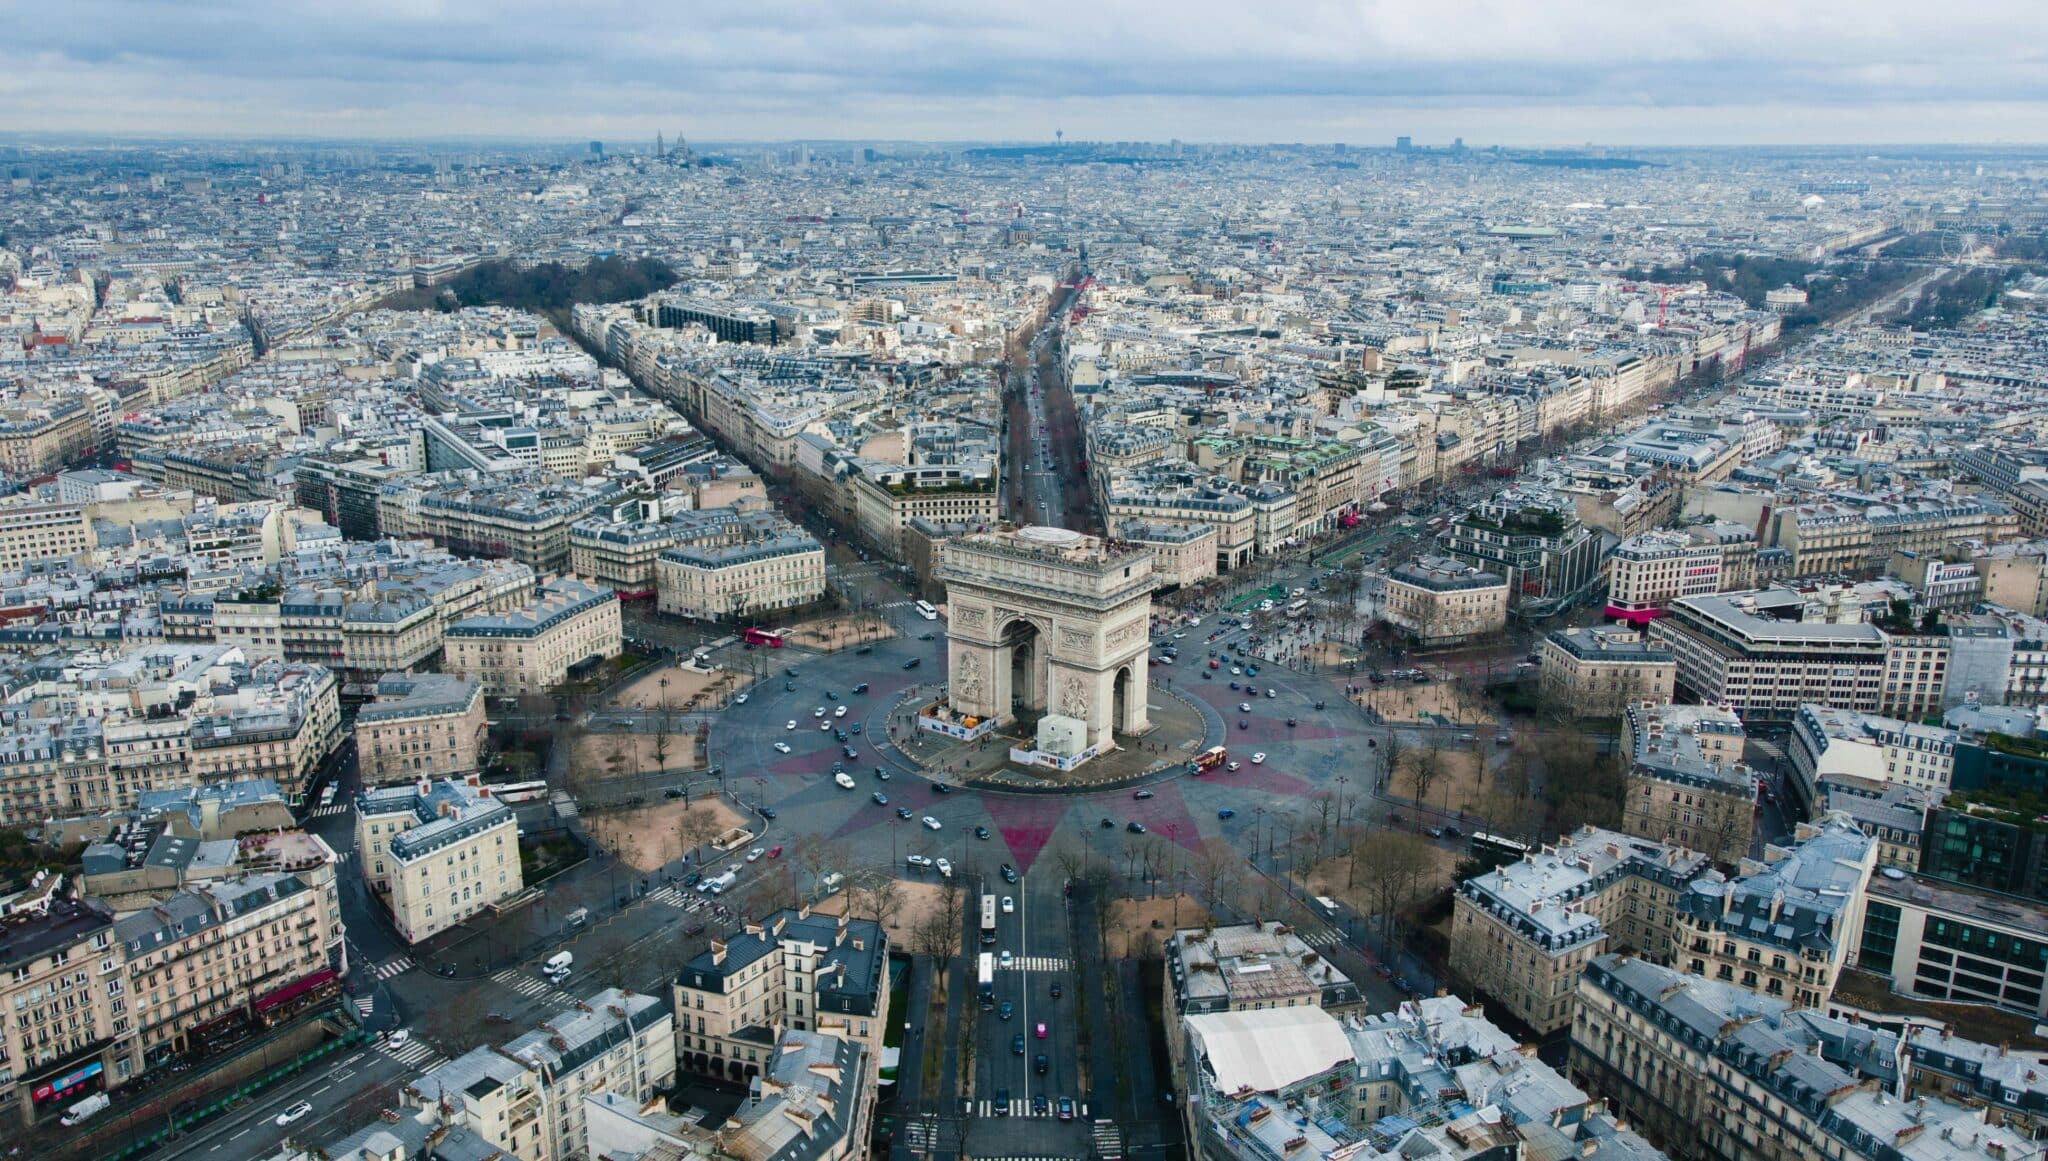
France is paying more to borrow, compared with Germany, than at any time since the eurozone crisis. At the end of last week, the French 10-year bond (OAT) was yielding about 157 basis points more than the German Bund. On Friday alone, the gap between the two widened by 30 basis points. On Monday the euro fell to its lowest level since May 2025, a slide that started when France’s budget failed to calm markets. This morning the euro won back part of that loss. A small bounce does not answer the bigger question, though: who will pay for France?
France is the eurozone’s second-largest economy, so its problems spread to everyone else in the bloc. Investors are moving money out of Paris and into Berlin. Every euro that moves raises the cost of keeping France’s budget afloat, and as that cost rises, more investors want out.
Money Is Moving From Paris to Berlin
The list of worries is long. The budget was poorly received. The government is divided and short of public support. A school pupils’ strike has turned violent. Inflation is rising. None of these alone would set off a run on French debt. Together, they have given bond traders a reason to sell.
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeThe gap between French and German yields is the number to watch. At 157 basis points it is not yet a crisis, but it is already higher than anything in the last 14 years. It is also happening while government bonds are selling off worldwide. The days when every government could borrow cheaply are over, and markets now charge each one according to how much they trust it. Right now they trust France less.
Why the ECB Can’t Help
In an earlier crisis, the European Central Bank would have cut rates or bought bonds to bring yields down. That is not an option with eurozone inflation at 3.8%. If the ECB loosened policy now, it would be rescuing France and raising prices for everyone else at the same time.
The ECB is also not the only central bank with limited room. The Federal Reserve raised rates for the first time in three years, and weak US jobs data on Friday only briefly calmed talk of another hike. Japan has it worse. The dollar is back above 158 yen and heading for 160. That raises the chance that Japan steps into the market again to support the yen, even after Bank of Japan Governor Kazuo Ueda said overnight that rates will keep rising.
Wall Street Is Relying on Two Sectors
US shares are taking all of this in their stride. The Nasdaq Composite rose 1.1% on Monday to a record close, and Nvidia also closed at a record. Underneath the headline, though, the market is narrow. Of the 11 sectors in the S&P 500, only technology and energy are trading above their 50-day averages. Real estate, utilities and financials are well below theirs.
That is not what a healthy bull market looks like. One reading is that AI is still in its early days and other sectors will catch up later. The other is that the whole market now depends on a single story, at a time when the AI build-out is getting more expensive. If that story falters, there is not much else holding prices up.
A Strait Reopens and Oil Slips
The day’s good news came from the Red Sea. Yemeni forces backed by Saudi Arabia drove the Houthis out of the port of Mocha and took back control of the Bab el-Mandeb Strait, the narrow sea route between the Red Sea and the Gulf of Aden. Oil fell on the news. Brent is still above $94, and the Strait of Hormuz is still the bigger problem. The G7 has agreed to release 100 million barrels from emergency stocks, and Middle Eastern crude exports have climbed back to pre-war highs. Some traders now think the worst is over. There is still no sign of a deal between Washington and Tehran.
Gold, normally a safe haven, has looked shaky. It fell close to $4,100 overnight before recovering to around $4,150. A strong dollar means gold could fall back to $4,000.
My Read
France is now the main risk inside the eurozone, and the usual way out is closed. The ECB can’t cut rates while inflation is near 4%, and markets no longer trust Paris to fix its own finances. Until the French government passes a budget investors believe, that 157-point gap will keep widening, the euro will stay weak and Europe will pay more for oil priced in dollars. Wall Street can ignore this for now, but Europe can’t.
Related Analysis