


London, 2 October 2026 — EBM Newsdesk Analysis — By Anthony Gill
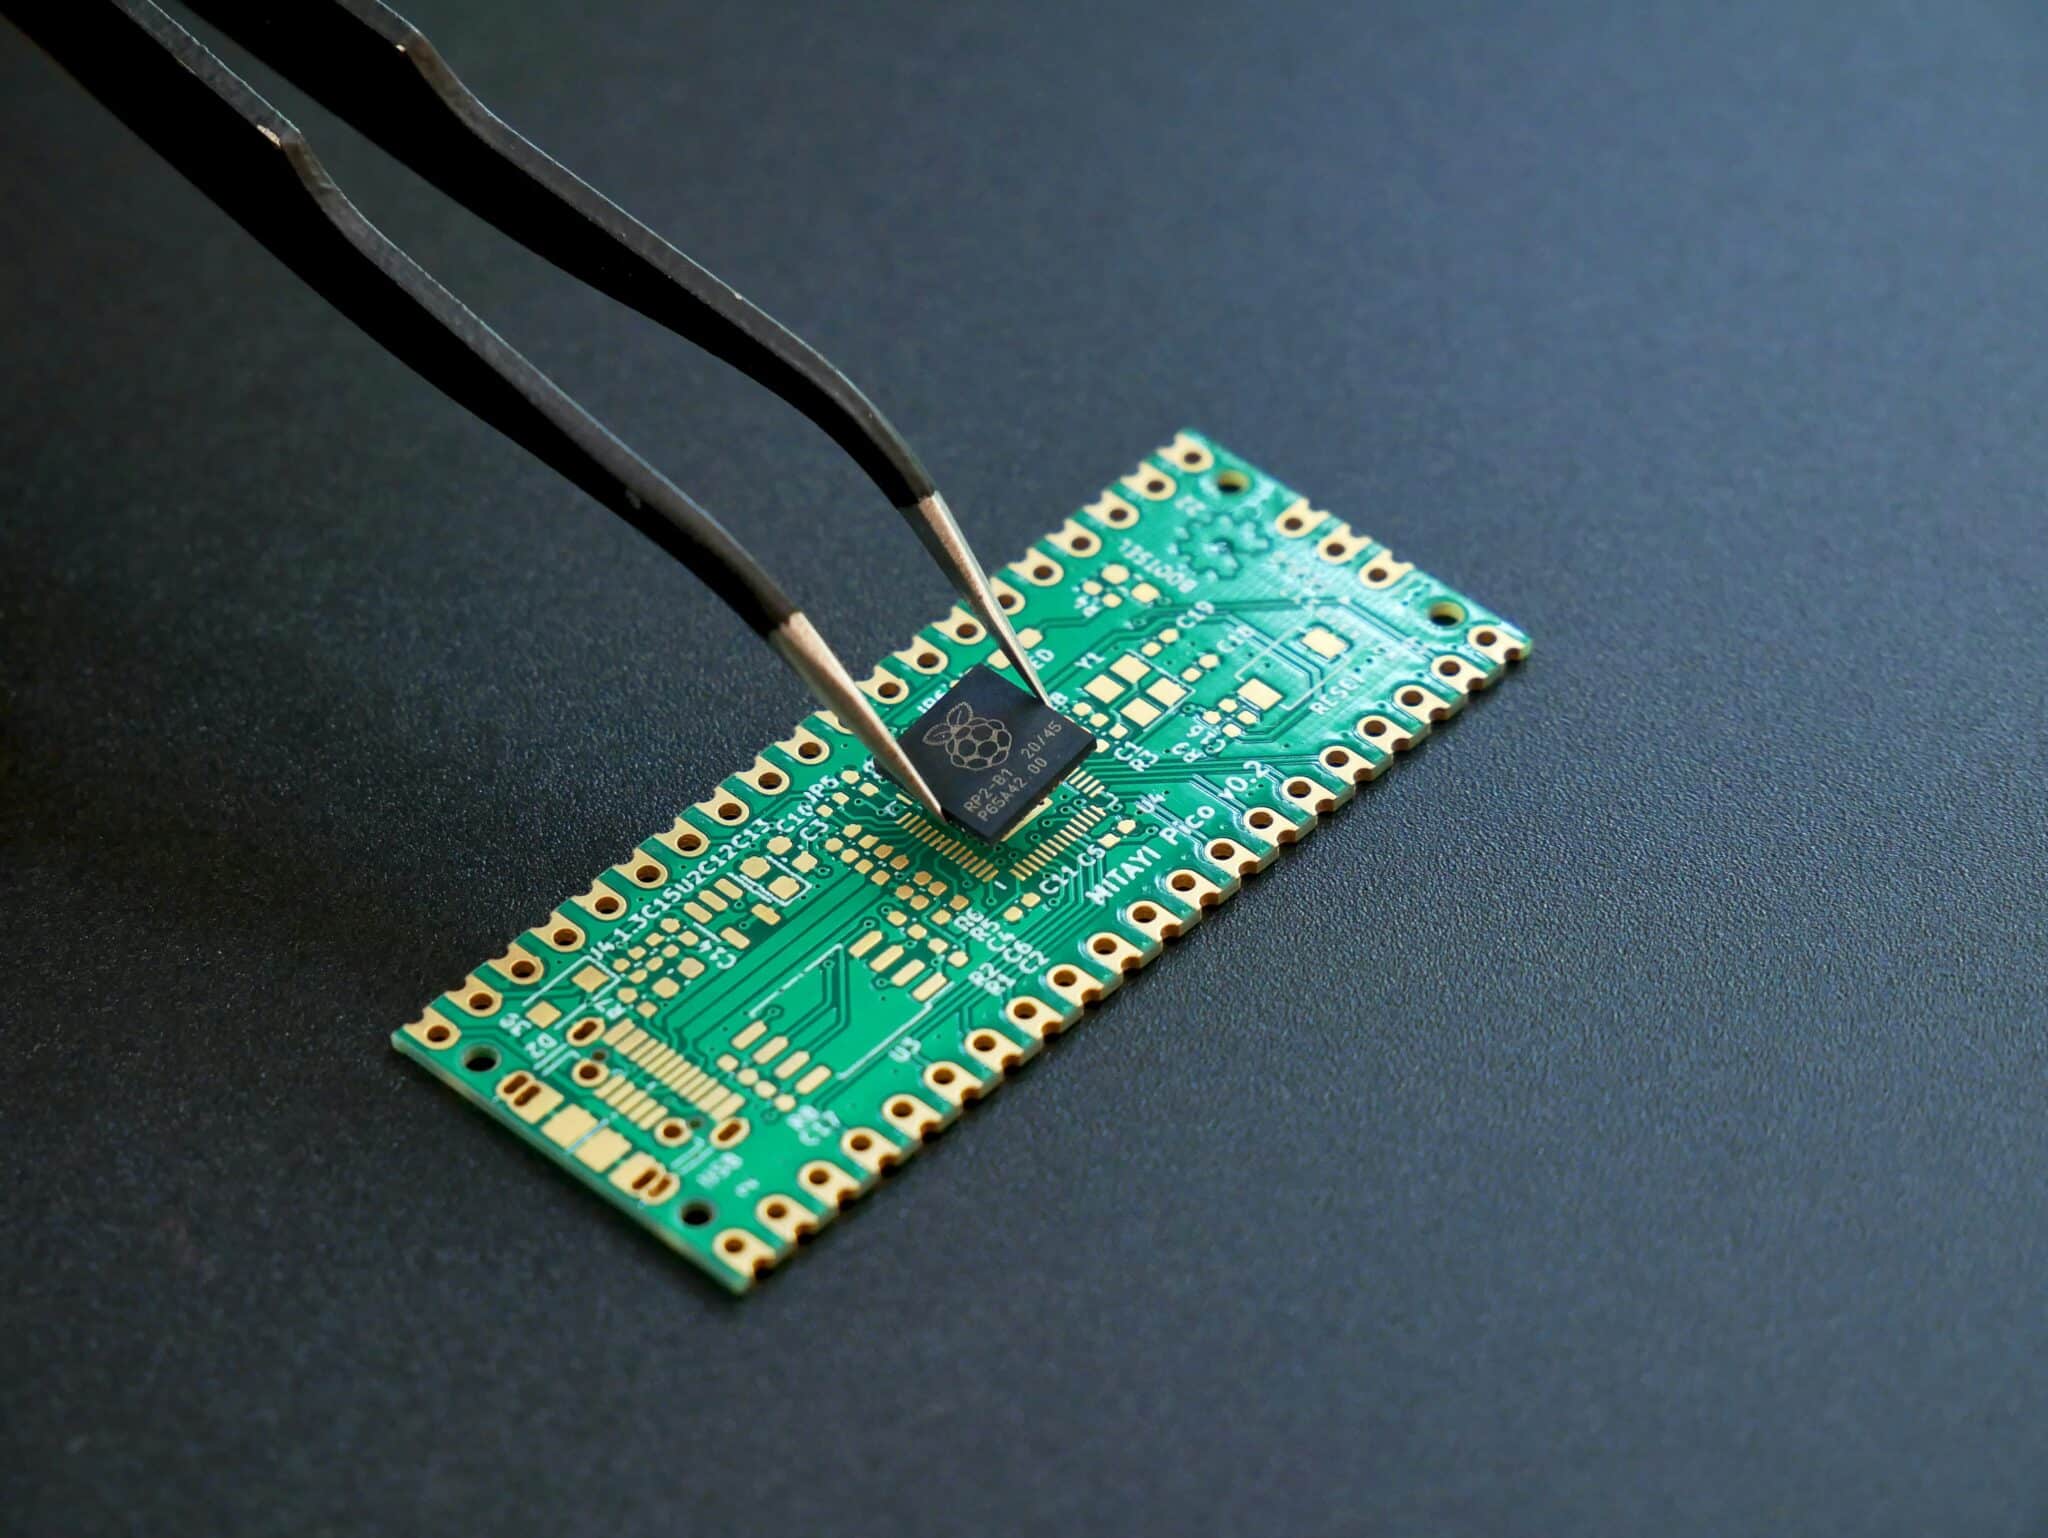
Late on Thursday, 1 October, the Financial Times reported that Amazon is seeking to offload about $8bn of advanced Nvidia chips to investors through a new vehicle designed to strengthen its balance sheet. The deal would move thousands of Grace Blackwell chips into a special-purpose vehicle, which Amazon would then lease them back from. The vehicle would raise money by issuing debt, and outside investors could take an equity stake of up to 10%. The chips are already installed in more than a dozen US data centres across five states, including Nevada and Virginia.
This is a quiet admission. Amazon expects to spend more than $200bn on capital investment this year, most of it on chips and data centres for its cloud business. Even for one of the world’s richest companies, that bill is now big enough to move off the balance sheet. For European investors, the lesson is that the AI spending boom is increasingly being paid for with borrowed money.
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeHow the Deal Works
It is an old financial technique applied to new hardware. Airlines have long sold planes to investors and leased them back. Property companies do the same with buildings. Amazon would do it with chips.
The appeal is simple. Amazon keeps using the chips but no longer has to carry their full cost as its own asset. Investors get a steady stream of lease payments backed by one of the strongest companies in the world. Amazon gets cash back to spend on the next wave of hardware.
Amazon isn’t the first. Meta used a similar structure last year to fund its giant Hyperion data centre with Blue Owl. Financial engineering is becoming as important to the AI race as the engineering itself.
The Catch
The risk is in the hardware itself. Unlike a plane or a building, an AI chip loses value fast. Nvidia releases a more powerful generation roughly every year, and the market for older chips can soften quickly. That makes them unusual collateral for long-term debt.
The deal also adds to a crowded debt market. AI companies are borrowing at record levels. SpaceX returned to the bond market for $20bn days after listing, and Anthropic has told would-be investors in its IPO filing that it lost almost $42bn last year. All that corporate borrowing competes with governments for investors, and it is one reason global borrowing costs keep rising.
What It Means for Europe
The AI trade is already showing strain at its edges. South Korea, whose chipmakers sell into the same boom, has just had the world’s worst stock market quarter. Even record profits haven’t protected chip stocks from sell-offs. European pension funds hold the hyperscalers through global index funds, and some are likely to be offered pieces of deals like this one. They should look carefully at what they are actually lending against.
The Bottom Line
There is nothing improper about Amazon’s plan. It is sensible treasury management. But it is also a signal. When the companies at the centre of the AI boom start selling the chips and renting them back, they are telling you the costs have outgrown even their balance sheets. That is fine while demand keeps rising. If it slows, the investors holding debt backed by last year’s chips will find out what that collateral is really worth.
Related Analysis
Big Tech’s Brussels Lobbying Power Is Leaving European Companies Fighting for Influence
China Threatens to Hit Back as Europe Builds a Weapon to Shut It Out of the Market
Oil Relief Lifts Markets, but Britain’s Energy Pain Is Only Postponed