



















Dublin, 26 September 2026 — EBM WEEKEND READ
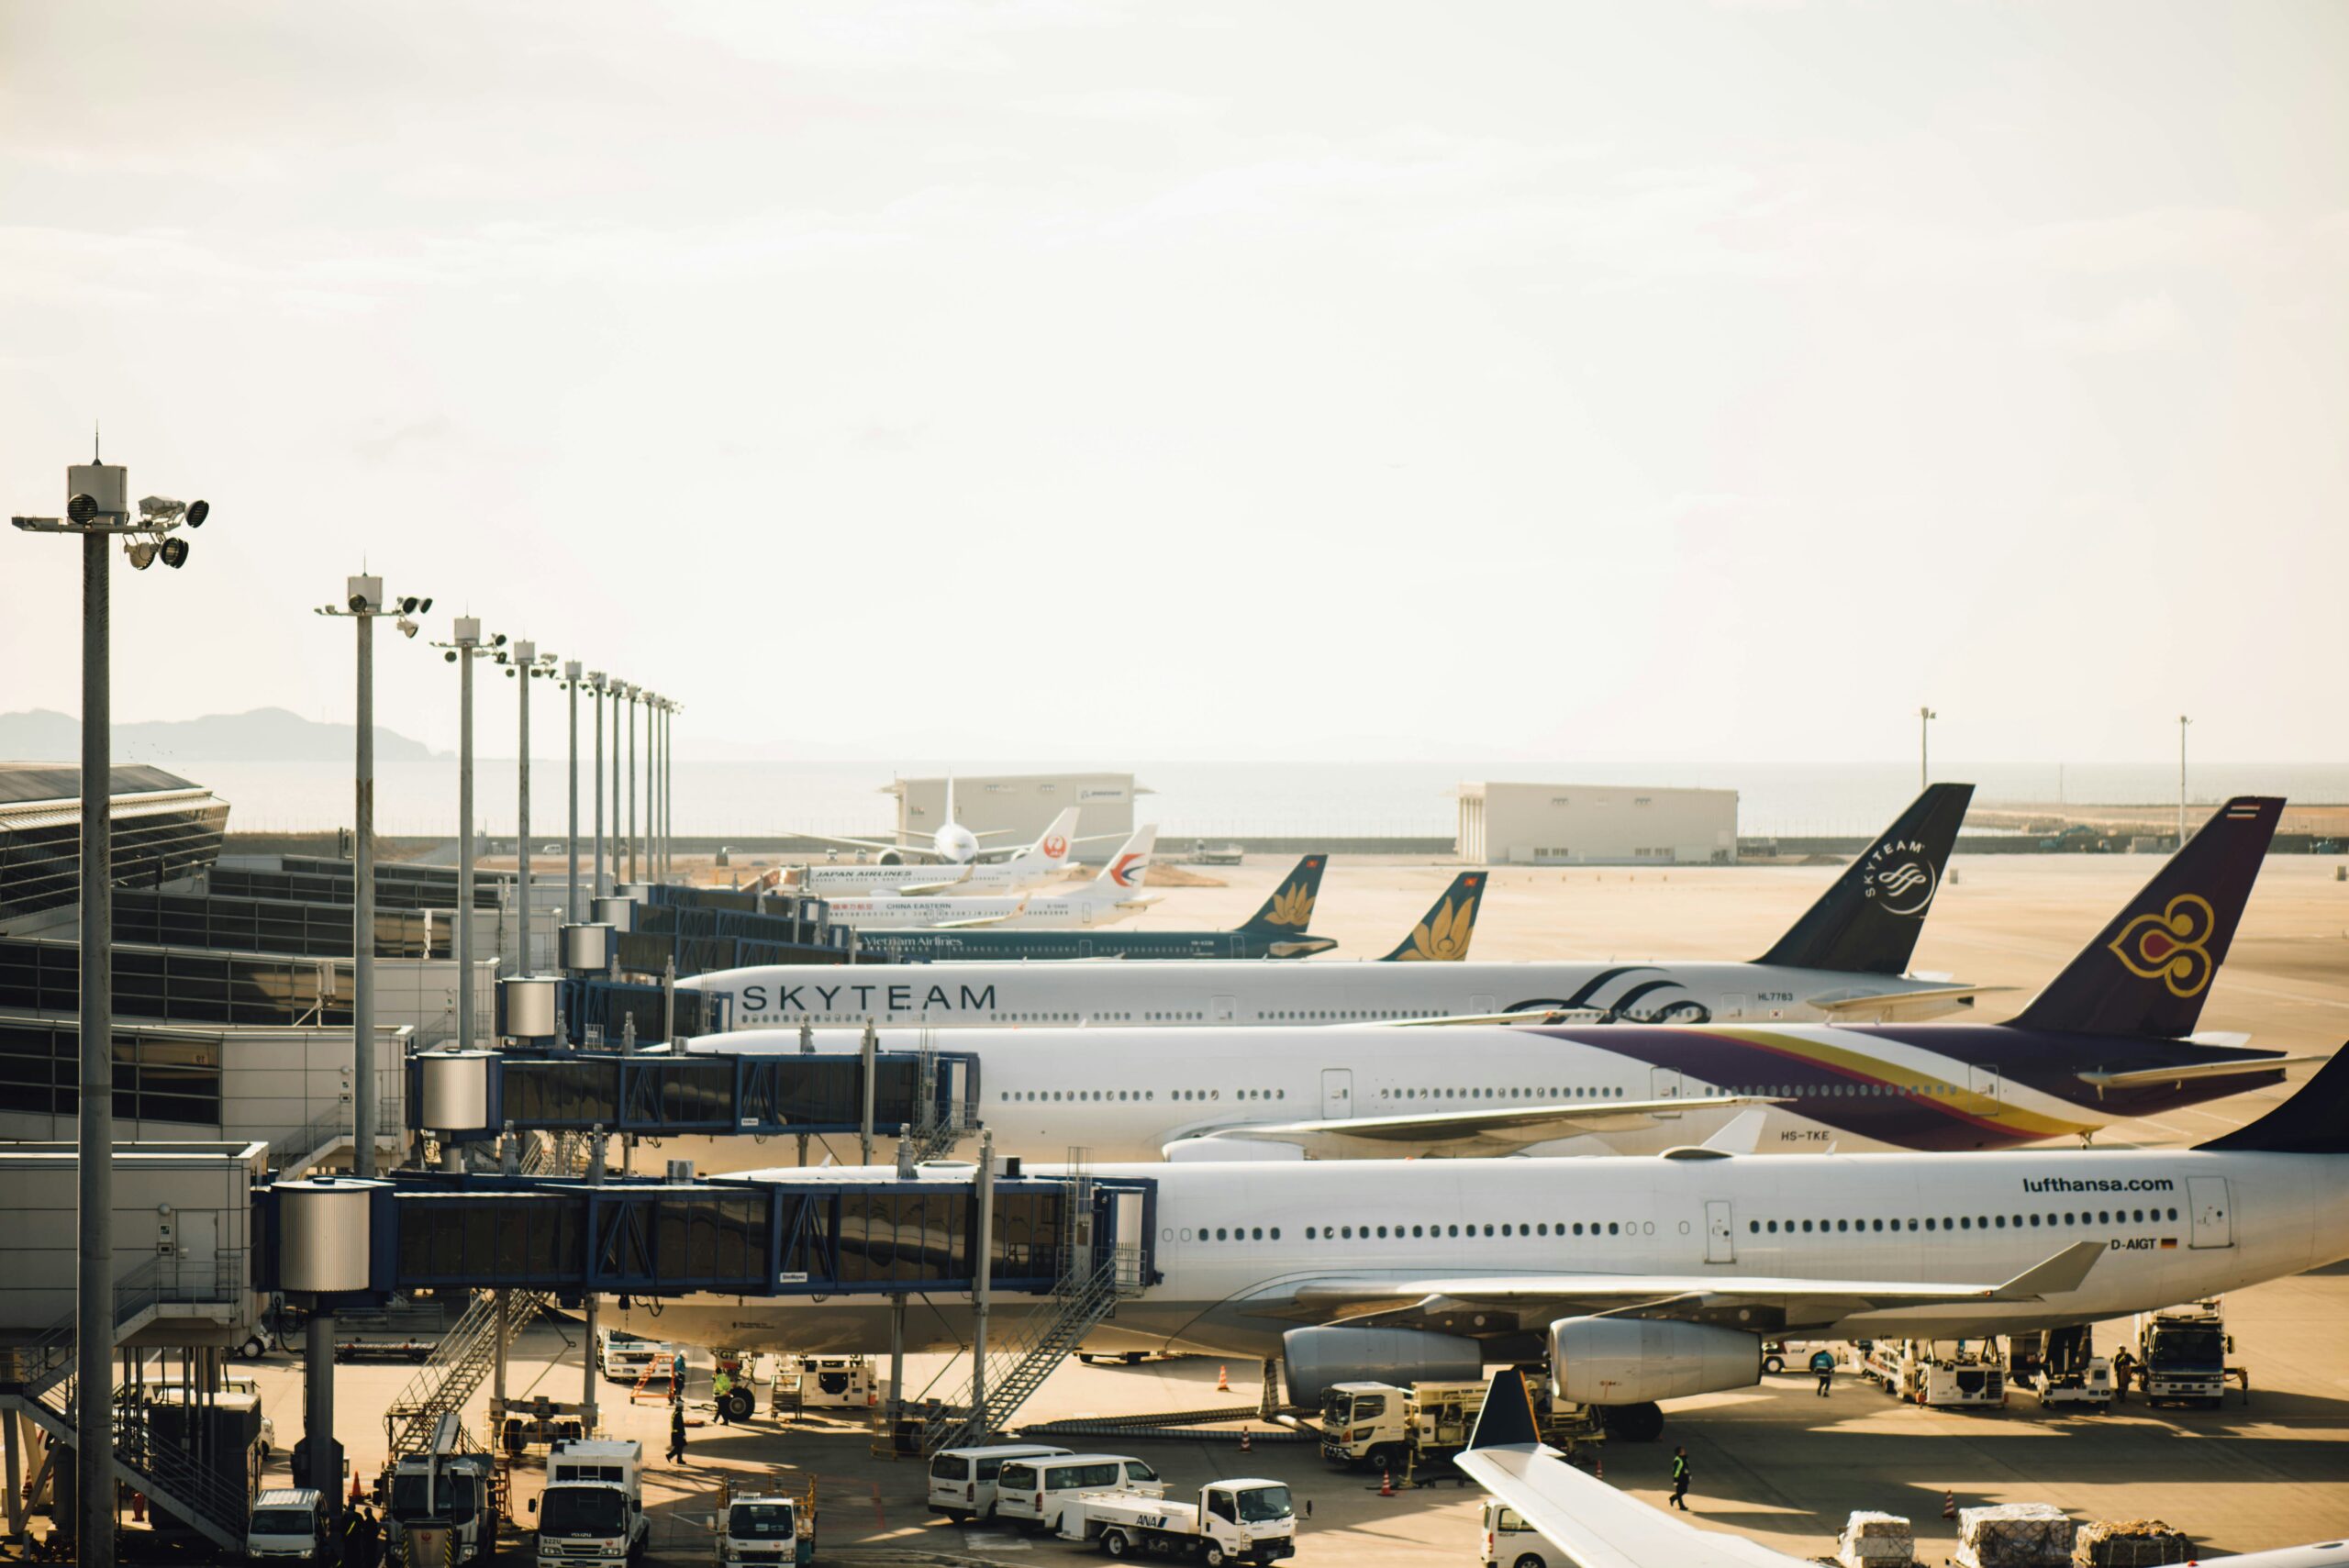
On Wednesday 23 September, Ryanair chief executive Michael O’Leary promised that his airline would not charge passengers a fuel surcharge, while predicting that the legacy carriers certainly would next summer. He went further, warning that fares may need to rise by 10%, 15% or even 20% if oil stays at current levels. His bluntest line concerned the weaker airlines: “Airlines who are currently loss-making will fail.” With the Hormuz crisis now in its eighth month, the real question is not whether he is right, but when the reckoning arrives.
O’Leary has an obvious interest in saying all this, and he has never hidden it. His forecast ends with Europe consolidated into four large airlines: British Airways, Lufthansa, Air France and Ryanair. Every rival that fails hands him market share. Yet a self-serving forecast can still be correct. The arithmetic behind this one points to a sharp shake-out in European aviation, and it will arrive later than most people expect.
Why the Pain Has Not Arrived Yet
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeThe size of the gap is striking. Ryanair has hedged roughly 80% of its fuel at about $67 a barrel through March 2027, while jet fuel has been trading at around $140. Even Ryanair, with the best cover in Europe, has trimmed its winter passenger target to 214 million from 216 million, to limit how much unhedged fuel it burns.
Everyone else is less protected, and the cover thins sharply after this year. Lufthansa has hedged about 80% of its 2026 needs at pre-crisis prices, but only about 40% for 2027. Even with this year’s cover, the airline warned in May that the kerosene spike would still add €1.7 billion to its costs, while Air France-KLM expects its fuel bill to rise by $2.4 billion. When the 2027 hedges roll off, those numbers get worse, not better.
Who Is Most Exposed
O’Leary has named names before. In April he suggested that two or three European airlines, including Wizz Air and airBaltic, could go bankrupt in October or November if oil stayed high. He added that this would be good for Ryanair because it would leave fewer competitors. Wizz Air’s chief executive József Váradi has pushed back, but in doing so he made the most important point in this whole debate: “Airlines don’t go bankrupt because they’re unprofitable—they go bankrupt because they run out of cash.”
That is the real test of the coming winter. A loss-making airline can survive for years if its lenders keep faith. The danger comes when fuel costs, rising borrowing costs and a weak winter season drain cash faster than banks are willing to refill it.
The Legacy Carriers’ Hidden Problem
The big network airlines look safer, but they carry a less obvious risk. Low-cost carriers such as easyJet and Wizz Air tend to hedge directly against jet fuel. Many traditional flag carriers hedge against crude oil or gasoil instead, adding jet fuel cover closer to departure. That matters because jet fuel prices have risen much faster than crude oil during this crisis, as the Strait of Hormuz cut off supplies of refined fuel. Morgan Stanley has warned that, in a worst case, Lufthansa’s fuel bill could rise by more than 35%, eroding up to 88% of its forecast 2026 operating profit.
Unlike the budget carriers, however, the legacy groups have options. They have scale, government relationships, and the ability to pass costs on through fuel surcharges, which is precisely the move O’Leary expects them to make next summer. That is why he describes the endgame as three groups and one airline, rather than four airlines. The mid-sized independents, with neither Ryanair’s cost base nor the flag carriers’ political protection, are the ones caught in the middle.
A Consolidation Market Opening Up
This is also why the deal-makers are already moving. The US fund circling EasyJet and the race among Europe’s biggest airlines for TAP Air Portugal both make more sense against this backdrop. When fuel stays expensive for longer than hedges last, weaker airlines become cheaper targets, and slots at crowded airports become the prize.
The global picture points the same way. The fuel shock is projected to cut global airline net profit to about $23 billion, roughly half of what the industry expected. For passengers, the result is likely to be fewer carriers, less choice on thinner routes and higher fares. Fuel normally makes up around a quarter of a ticket price, so the increases O’Leary describes are plausible rather than alarmist.
The Verdict
My view is that O’Leary is talking his own book, but the numbers are on his side. The crisis that began with Iranian strikes on tankers in Hormuz has so far been absorbed by hedges written in calmer times. That protection runs out during 2027, just as the quiet winter season tests every airline’s cash reserves.
The survivors will be the airlines with deep hedges, low costs, strong balance sheets or a government willing to help, and ideally more than one of those. Airlines with none of them are running out of time. A deal to reopen Hormuz would ease the pressure, but it would not rebuild the cash already spent. Europe’s airline industry has been waiting for its consolidation moment for two decades, and this fuel shock may finally deliver it. Whether passengers will like the result is another matter entirely.
Related Analysis