




















Louisville, Kentucky, 21 September 2026 — EBM Newsdesk Analysis — By Katie Winearls, Editor-in-Chief
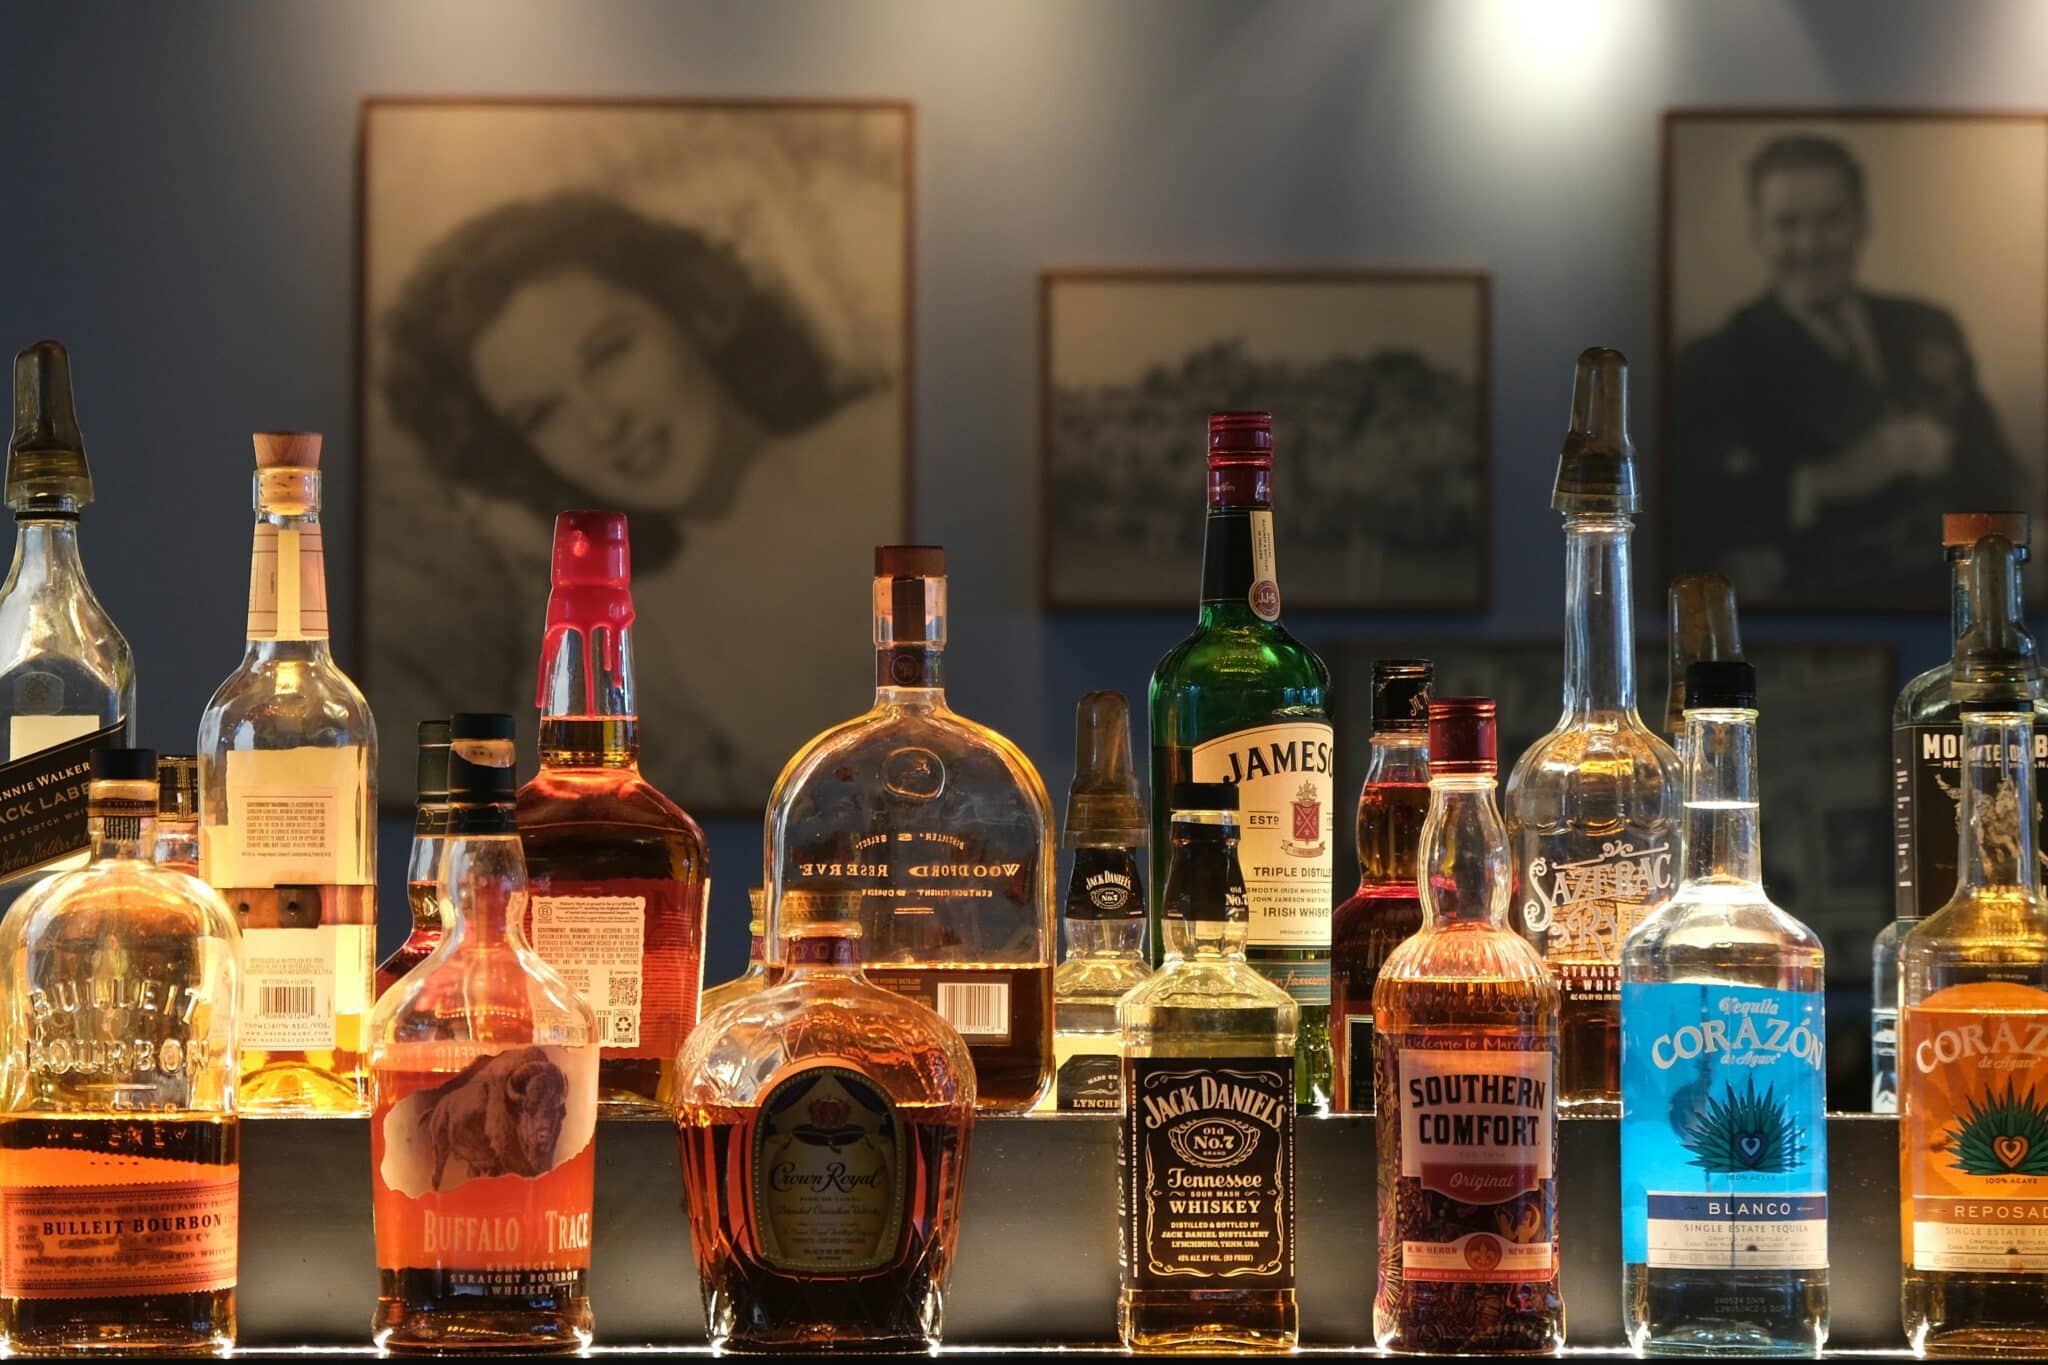
Sazerac, the privately held US spirits company behind Southern Comfort and Fireball, has launched a voluntary takeover offer for all shares of Berentzen-Gruppe, the German beverage maker best known for its apple-flavoured schnapps. The offer values Berentzen at €5.55 per share in cash — a roughly 68% premium to its unaffected three-month volume-weighted average share price on Xetra before 16 September. Both Berentzen’s executive board and supervisory board support the deal and intend to formally recommend it to shareholders once Germany’s financial regulator, Bafin, has reviewed the offer document.
The scale involved is genuinely lopsided. Berentzen carried a market capitalisation of roughly €35 million before news of the talks broke, and shares jumped about 22% to a 14-month high on confirmation of the negotiations alone. Sazerac, by contrast, is a company that has bid roughly $15 billion for Brown-Forman in the past and acquired UK-based Au Vodka for around €350 million — meaning this deal is a rounding error against its usual scale of ambition, not a stretch acquisition.
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeThat gap is precisely the point. Sazerac’s strategy for years has centred on buying young or underperforming brands that larger conglomerates no longer see as a priority, then applying its own distribution muscle to brands that were previously starved of it. The company already has a direct history with exactly this playbook: it bought Southern Comfort and Tuaca from Brown-Forman for $543.5 million in 2016, and Early Times from the same seller in 2020, both cases of picking up heritage brands a bigger portfolio manager had deprioritised. Berentzen, a company with more than 260 years of history spanning spirits, non-alcoholic drinks and fresh juice systems, fits the same profile: a recognisable name that a small, thinly-traded German public company has likely struggled to give the sales and marketing investment it would need to grow meaningfully.
Berentzen’s own board framed the logic in similar terms, with executives Oliver Schwegmann and Ralf Brühöfner calling it “an outstanding opportunity” specifically because innovation, sales capability and internationalisation are the areas the company most needs to strengthen — capabilities a much larger US distribution partner can supply far faster than Berentzen could build them alone as a standalone listed micro-cap.
The mechanics are straightforward by takeover standards. The offer requires acceptance from just 50% plus one share of Berentzen’s stock, no regulatory clearances are needed, and Sazerac expects the deal to close in the fourth quarter of 2026. Once complete, Berentzen will be delisted from the Frankfurt Stock Exchange’s General Standard segment — ending its run as a public company after Sazerac becomes its controlling owner.
Where we stand: This is a small deal by dollar value and a much bigger one by what it signals. A privately held American spirits company with no obligation to explain its capital allocation to public markets is once again reaching into Europe to pick up a heritage brand a public listing has left undercapitalised. Berentzen’s 68% premium tells its own shareholders the market had been mispricing it for some time. Whether Sazerac can actually do more with the brand than Berentzen’s own board could as a standalone company is the only question that will matter in three years — the premium just tells you what the market thinks the odds are today.