




















London, 21 September 2026 — EBM Newsdesk Analysis — By Brad Adams
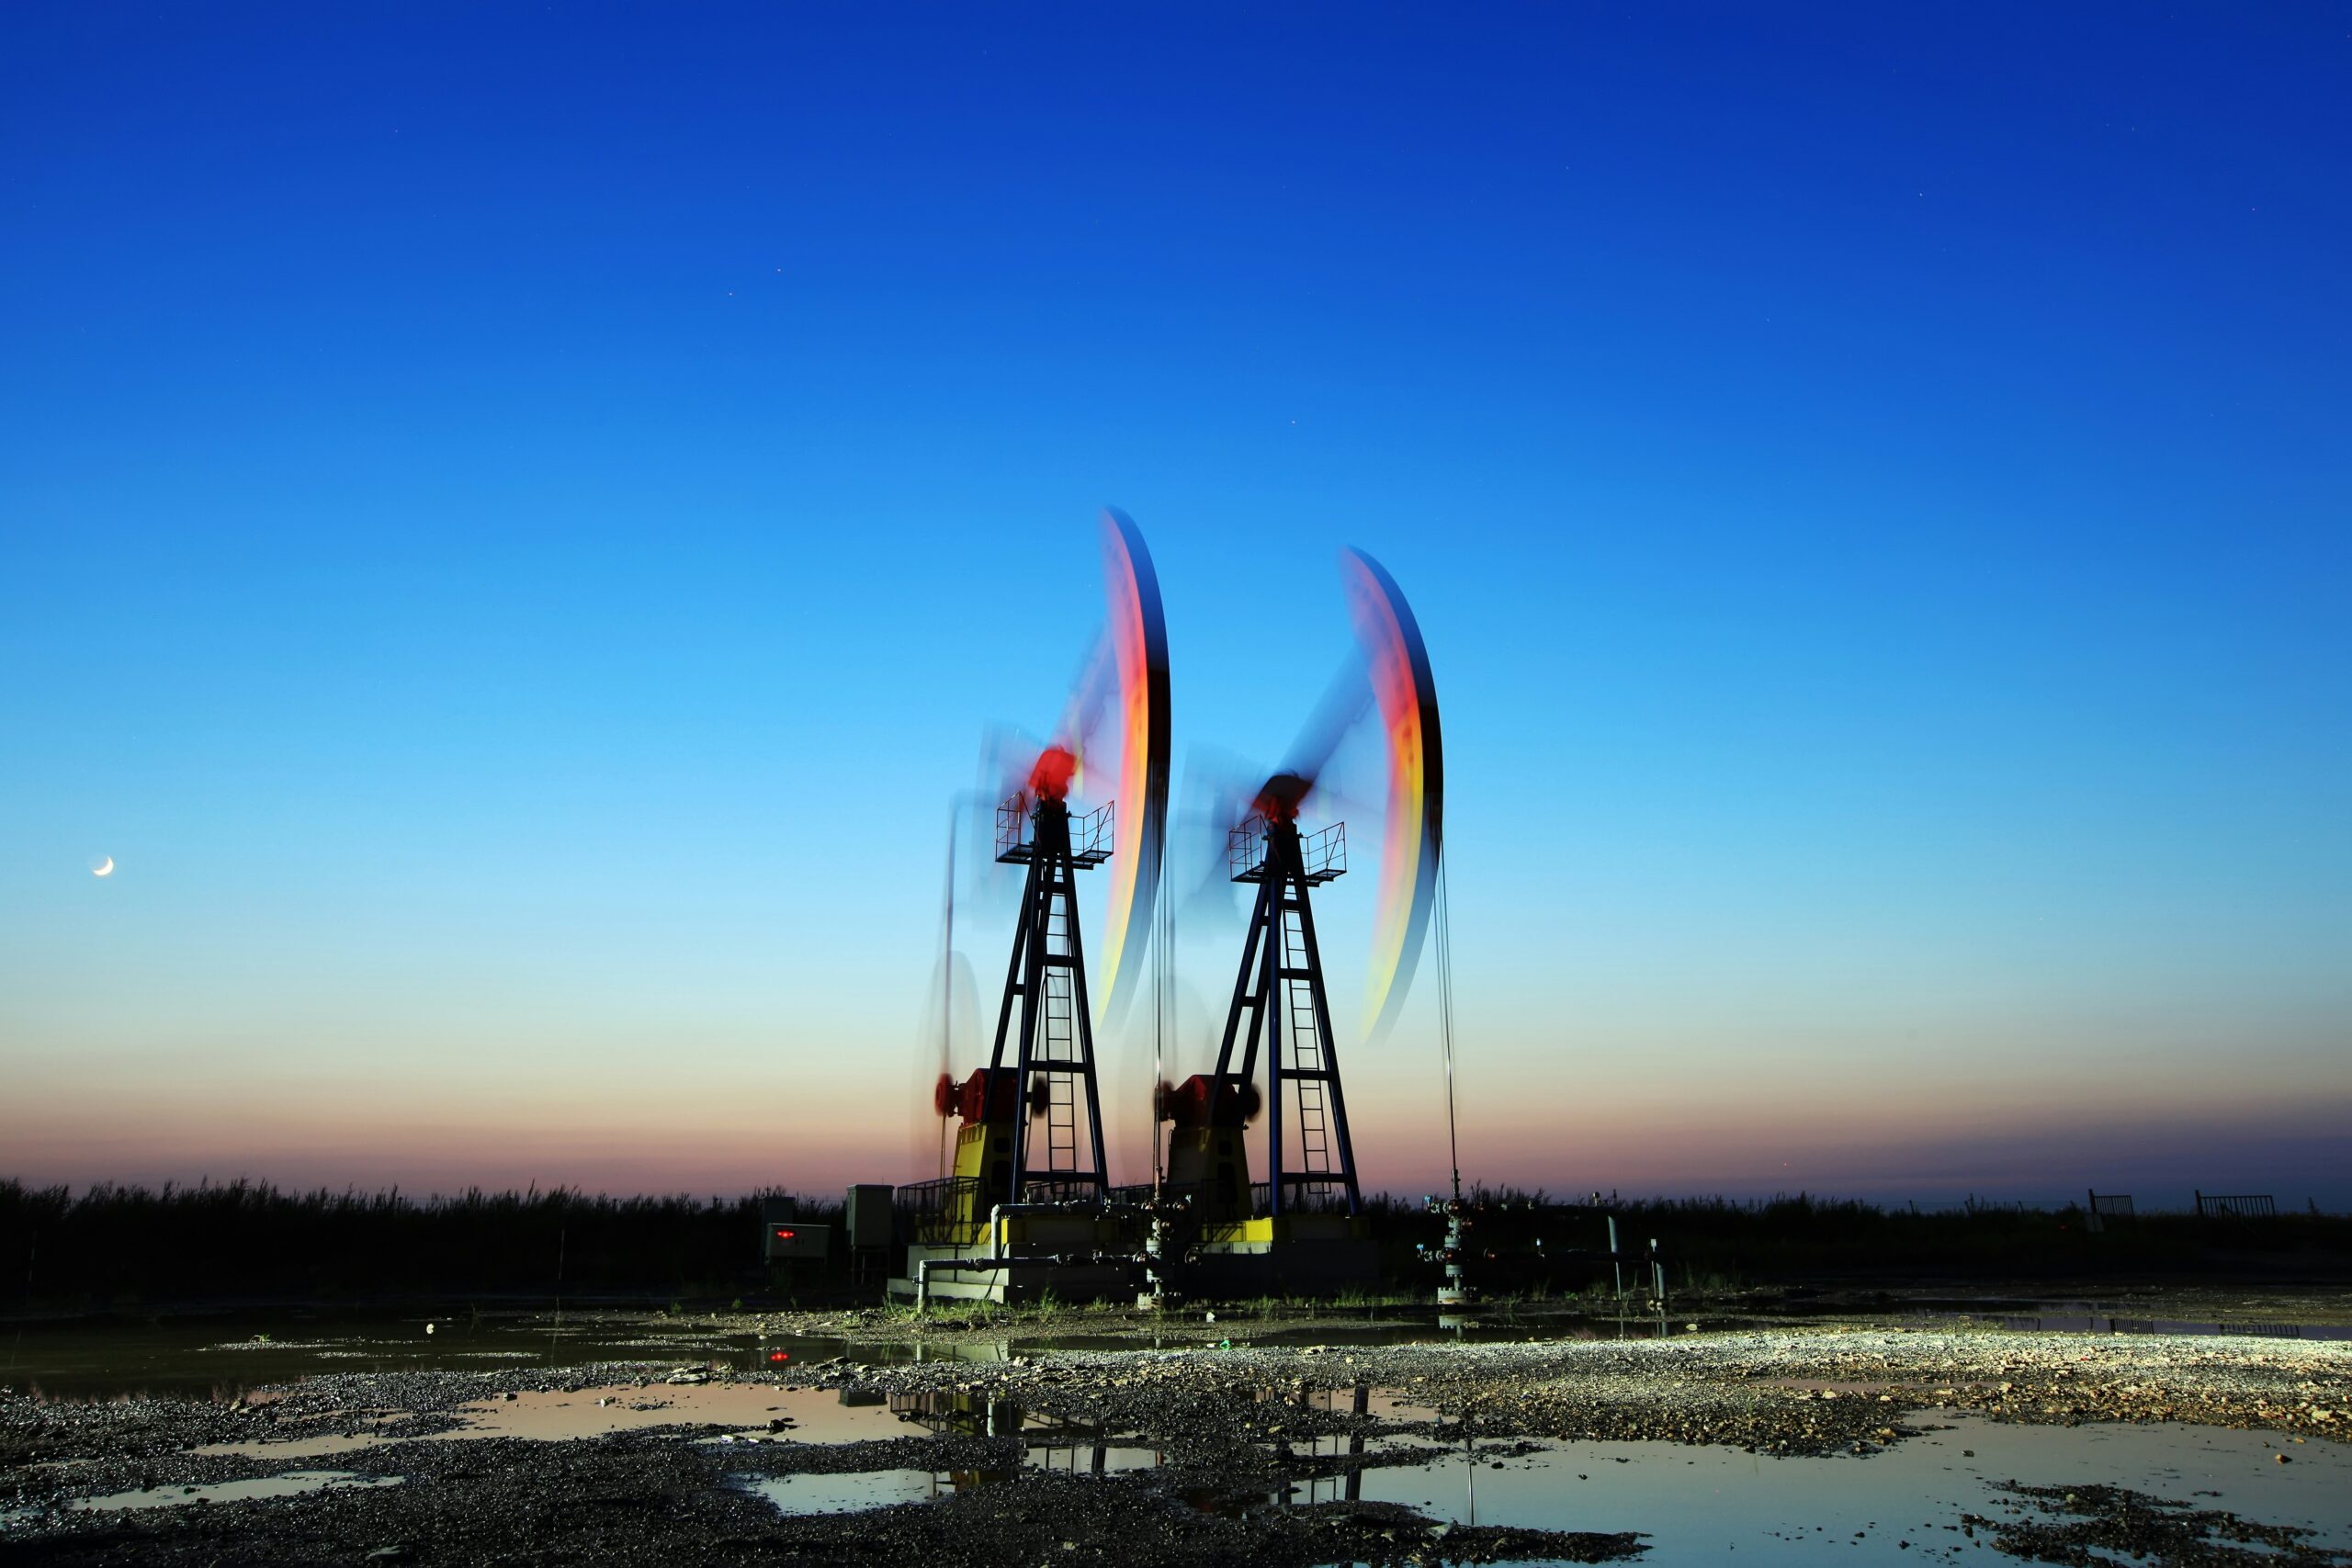
Oil fell to its lowest level in more than a week on Monday, with Brent crude down 2.08% to $101.71 a barrel and US WTI losing 2.14% to $98.15, on hopes that diplomacy in the Iran war might get a genuine chance this week around a UN meeting. Both benchmarks touched their lowest levels since 10 September. “It seems that a degree of risk premium is being removed from oil prices on hopes that a diplomatic path to de-escalate the US-Iran war may arrive this week,” Tim Waterer, chief market analyst at KCM Trade, said — while adding the honest caveat that whether that hope is warranted “is another question.”
That caveat is doing a lot of work, because the price drop arrived just two days after Yemen’s Iran-backed Houthis attacked what they called “sensitive” sites in the Saudi capital, Riyadh, with missiles and drones, alongside a strike on an Aramco facility in the Red Sea export hub of Yanbu. It follows an earlier assault this month that hit energy infrastructure in Abha, Khamis Mushait, Jazan and Najran, injuring more than 70 civilians and forcing temporary shutdowns at several sites. Markets are, in effect, pricing a de-escalation story and an active attack pattern simultaneously — which is less contradictory than it sounds, because traders are betting on the direction of travel rather than the absence of risk.
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeThe reason the market can look past continued strikes and still push prices down is that Saudi Arabia’s actual export capacity has been recovering. Aramco’s East-West pipeline, hit by the Houthi attacks, prompted the kingdom to reroute more crude through the Strait of Hormuz this month and next after halting shipments through Yanbu — and that rerouting has worked well enough that Saudi exports climbed back above 4 million barrels per day in September, up from a low of 2.4 million bpd in August, the weakest since EBM tracked the Hormuz shipping crunch at its worst. A functioning bypass route matters more to price than any single attack, because it’s evidence the war hasn’t actually cut off Saudi supply even when it succeeds in disrupting individual facilities.
There’s a genuinely unusual diplomatic wrinkle behind this specific dip: China has reportedly asked Iran to help rein in the Houthis, after Saudi Arabia appealed directly to Beijing following the Riyadh attacks. That’s a notable shift in who’s doing the diplomatic work — Goldman Sachs has already flagged Hormuz and Red Sea shipping attacks as the single most likely driver of a scenario where Brent spikes above $120 next year, and a Chinese-brokered restraint on Iran’s own proxies would remove exactly the variable Goldman’s own analysts consider most dangerous. Whether Tehran actually has the leverage to rein in the Houthis, or the willingness to spend that leverage on Riyadh’s behalf, is the real question the market is betting on this week.
EBM Takeaway: EBM has tracked this same pattern since the war began: oil prices move on the distance between the current price and any plausible ending, not on the raw body count of any single attack. Monday’s dip isn’t evidence the war is ending — it’s evidence traders think a diplomatic window might open this week, which is a much cheaper thing to price in than an actual ceasefire. Goldman’s own base case still isn’t the $120 scenario, but its own analysts have been clear about what would trigger it: more intense shipping attacks in Hormuz and the Red Sea, the exact pattern still playing out in Riyadh and Yanbu even as the price falls. This is a market pricing hope, not resolution — and hope, on the war’s own eight-month track record, has a poor conversion rate into anything that actually lasts.