
























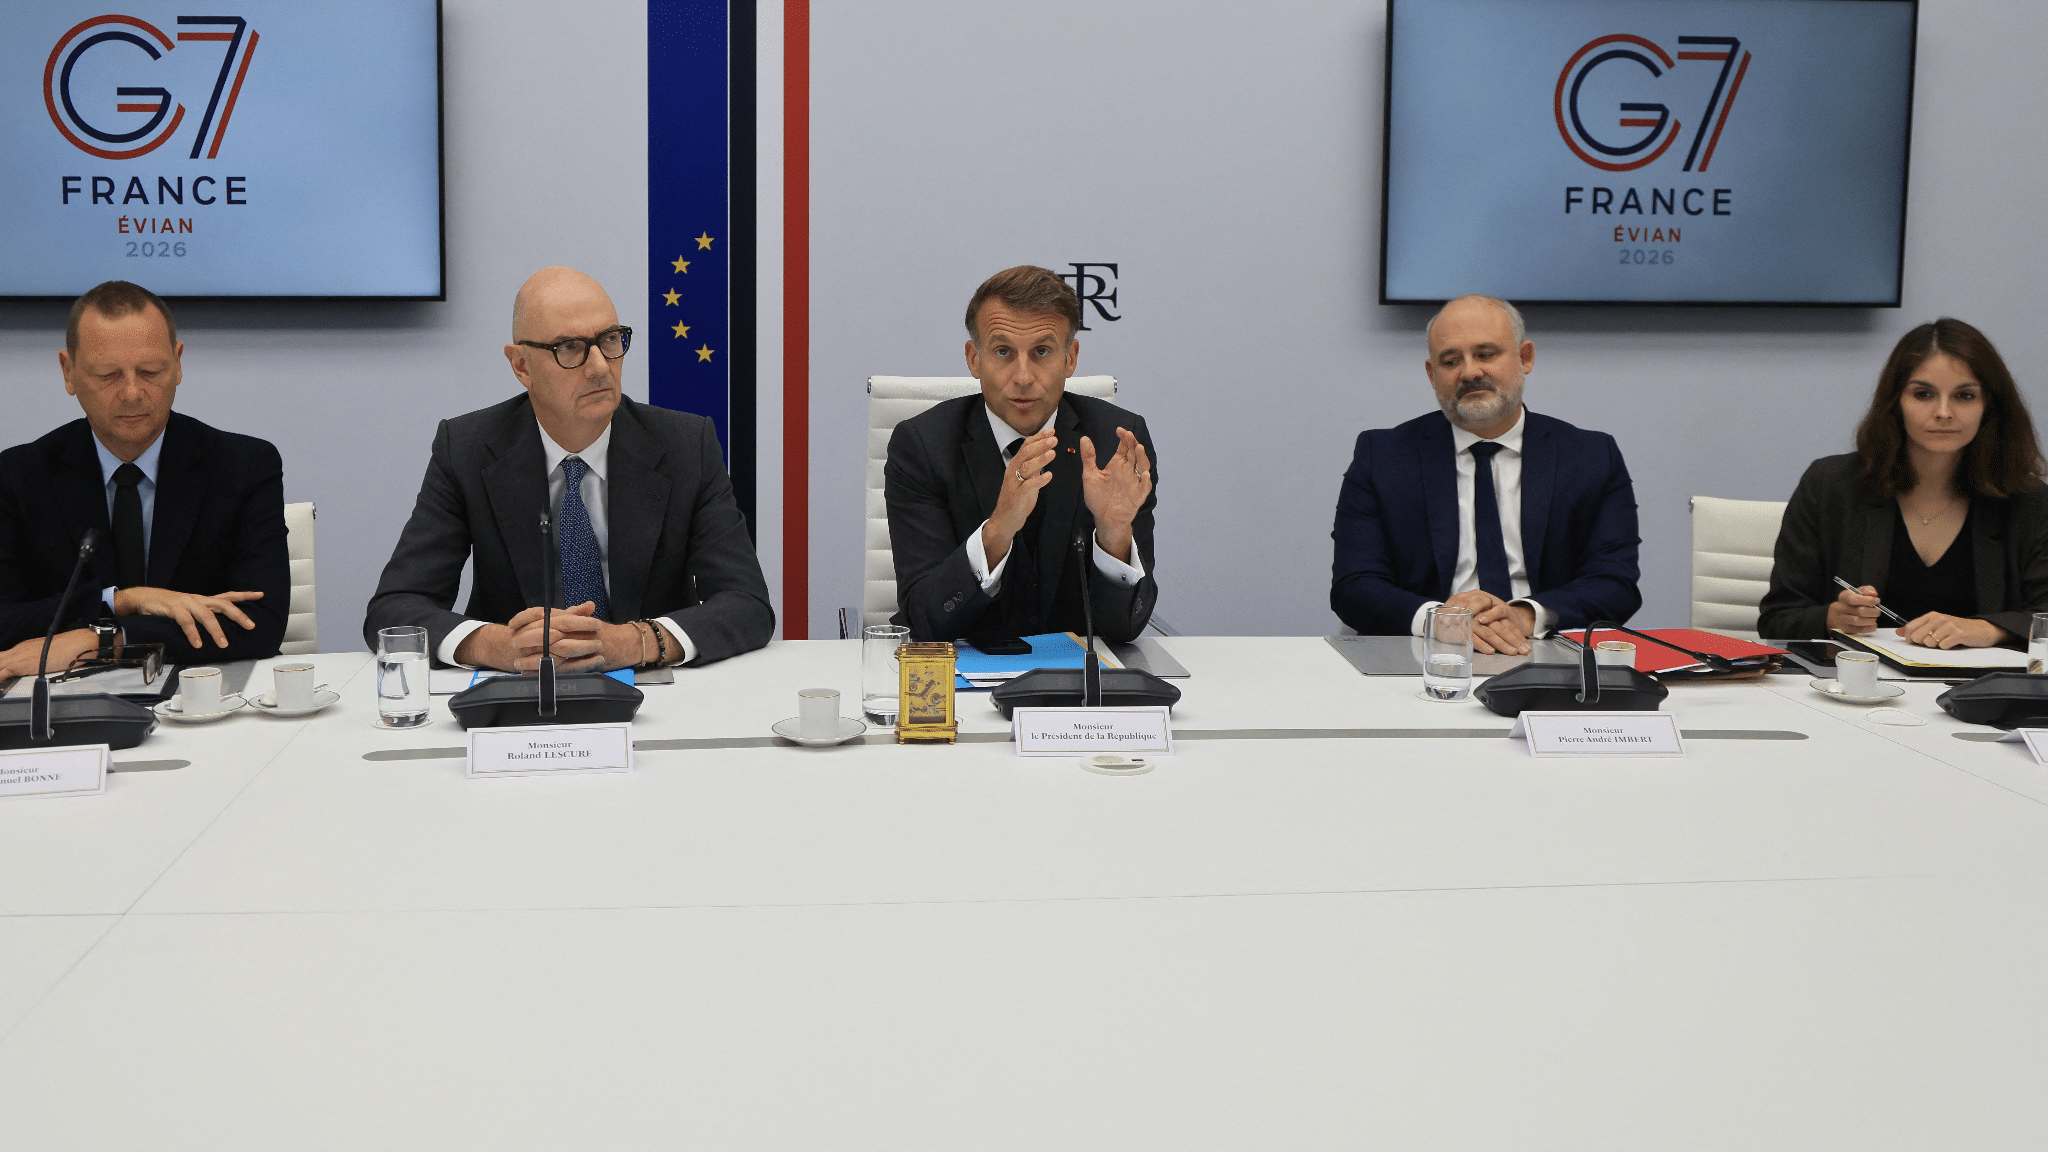
On 2 October, G7 leaders pledged a coordinated release of 100 million barrels of oil and diesel through the International Energy Agency (IEA) over four months, with a substantial diesel release in the first 20 days, according to their joint statement. The move followed record fuel prices on both sides of the Atlantic. For businesses, the useful question is not whether the headline lowers prices overnight, but how much relief a stockpile can deliver when the shortage sits in refined fuel rather than crude.
Why diesel became the pressure point
US diesel hit a record $6.53 a gallon in the week of 21 September, according to the Energy Information Administration (EIA), up from $3.46 in mid-January, and eased to $6.18 by 12 October. In the European Union, the European Commission reported a record average of €2.24 a litre in late September, against €1.59 before the Iran war began on 28 February. The IEA’s October report explains why: Gulf crude exports have recovered to about three-quarters of prewar levels, but Middle East shipments of refined products remain below half, and Russian refineries have been damaged.
How fuel costs reach operating costs and margins
Bain & Company estimates that fuel now makes up 25% to 30% of trucking operating costs, up from about 21% in 2024. It notes that UPS raised its fuel surcharge from 21% before the Iran conflict to 29.5% by 21 September. For a shipper spending $50 million a year on truckload base rates, Bain calculates, fuel charges would be about $10.5 million at a 21% surcharge but $12.5 million to $15 million at 25% to 30%. That is an extra $2 million to $4.5 million a year before renegotiation. Costs then pass from carriers to shippers, retailers and consumers, and firms that cannot reprice quickly absorb the difference in their margins.
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeWhat a reserve release can and cannot do
The scale is modest. The IEA’s October report puts 2026 global oil demand at about 102.4 million barrels a day, so 100 million barrels equals roughly one day of consumption. The G7 statement counts commitments already fulfilled, and the IEA describes the step as accelerating delivery of volumes agreed in March, so the emphasis is speed rather than new supply. Prioritising diesel matters, since the IEA expects tight gasoil markets to persist well into 2027, with inventory rebuilding unlikely before the second half of next year. Any relief should be treated as temporary.
Reading energy headlines with context
In mid-October, the IEA reported Brent futures near $107 a barrel but physical North Sea Dated crude near $134, a gap that shows why no single benchmark tells the whole story. Wholesale diesel has eased from September’s record above $200 a barrel, yet remains nearly double the price of crude, according to the IEA. Weighing futures, physical prices, inventories and official statements together gives a steadier picture, and outlets such as Issue Red that link their sources help readers check what a headline actually establishes.
Frequently asked questions
Will the G7 release lower diesel prices quickly?
Not necessarily. Reserve stock has to be delivered and distributed, so pump prices usually lag wholesale moves. The IEA also warns that weak refining margins could force run cuts in Europe and Asia, which would tighten supply again.
Why is diesel treated differently from crude oil?
Crude must be refined, and refineries make a mix of fuels. The IEA says global diesel availability was 1.7 million barrels a day lower in the third quarter than a year earlier, so diesel can stay scarce even as crude exports recover.
How should businesses respond to fuel price volatility?
Bain suggests pegging surcharges in carrier contracts to the EIA’s weekly diesel price, limiting how often carriers change surcharge tables, and shifting time-tolerant freight to rail. Reducing empty miles and checking supplier freight charges also help.
Conclusion: reserves buy time, not certainty
The G7 decision shows how quickly an energy shock becomes a business problem, and how limited the tools for easing it are. Emergency stocks can soften a spike, but refining capacity and geopolitical risk set the path afterwards. The practical response is to measure fuel exposure, negotiate contract terms that share volatility, and plan for tight diesel into 2027 rather than bet on a quick fall.






