

London, 20 October 2026 — EBM Weekend Read — By Brad Adams
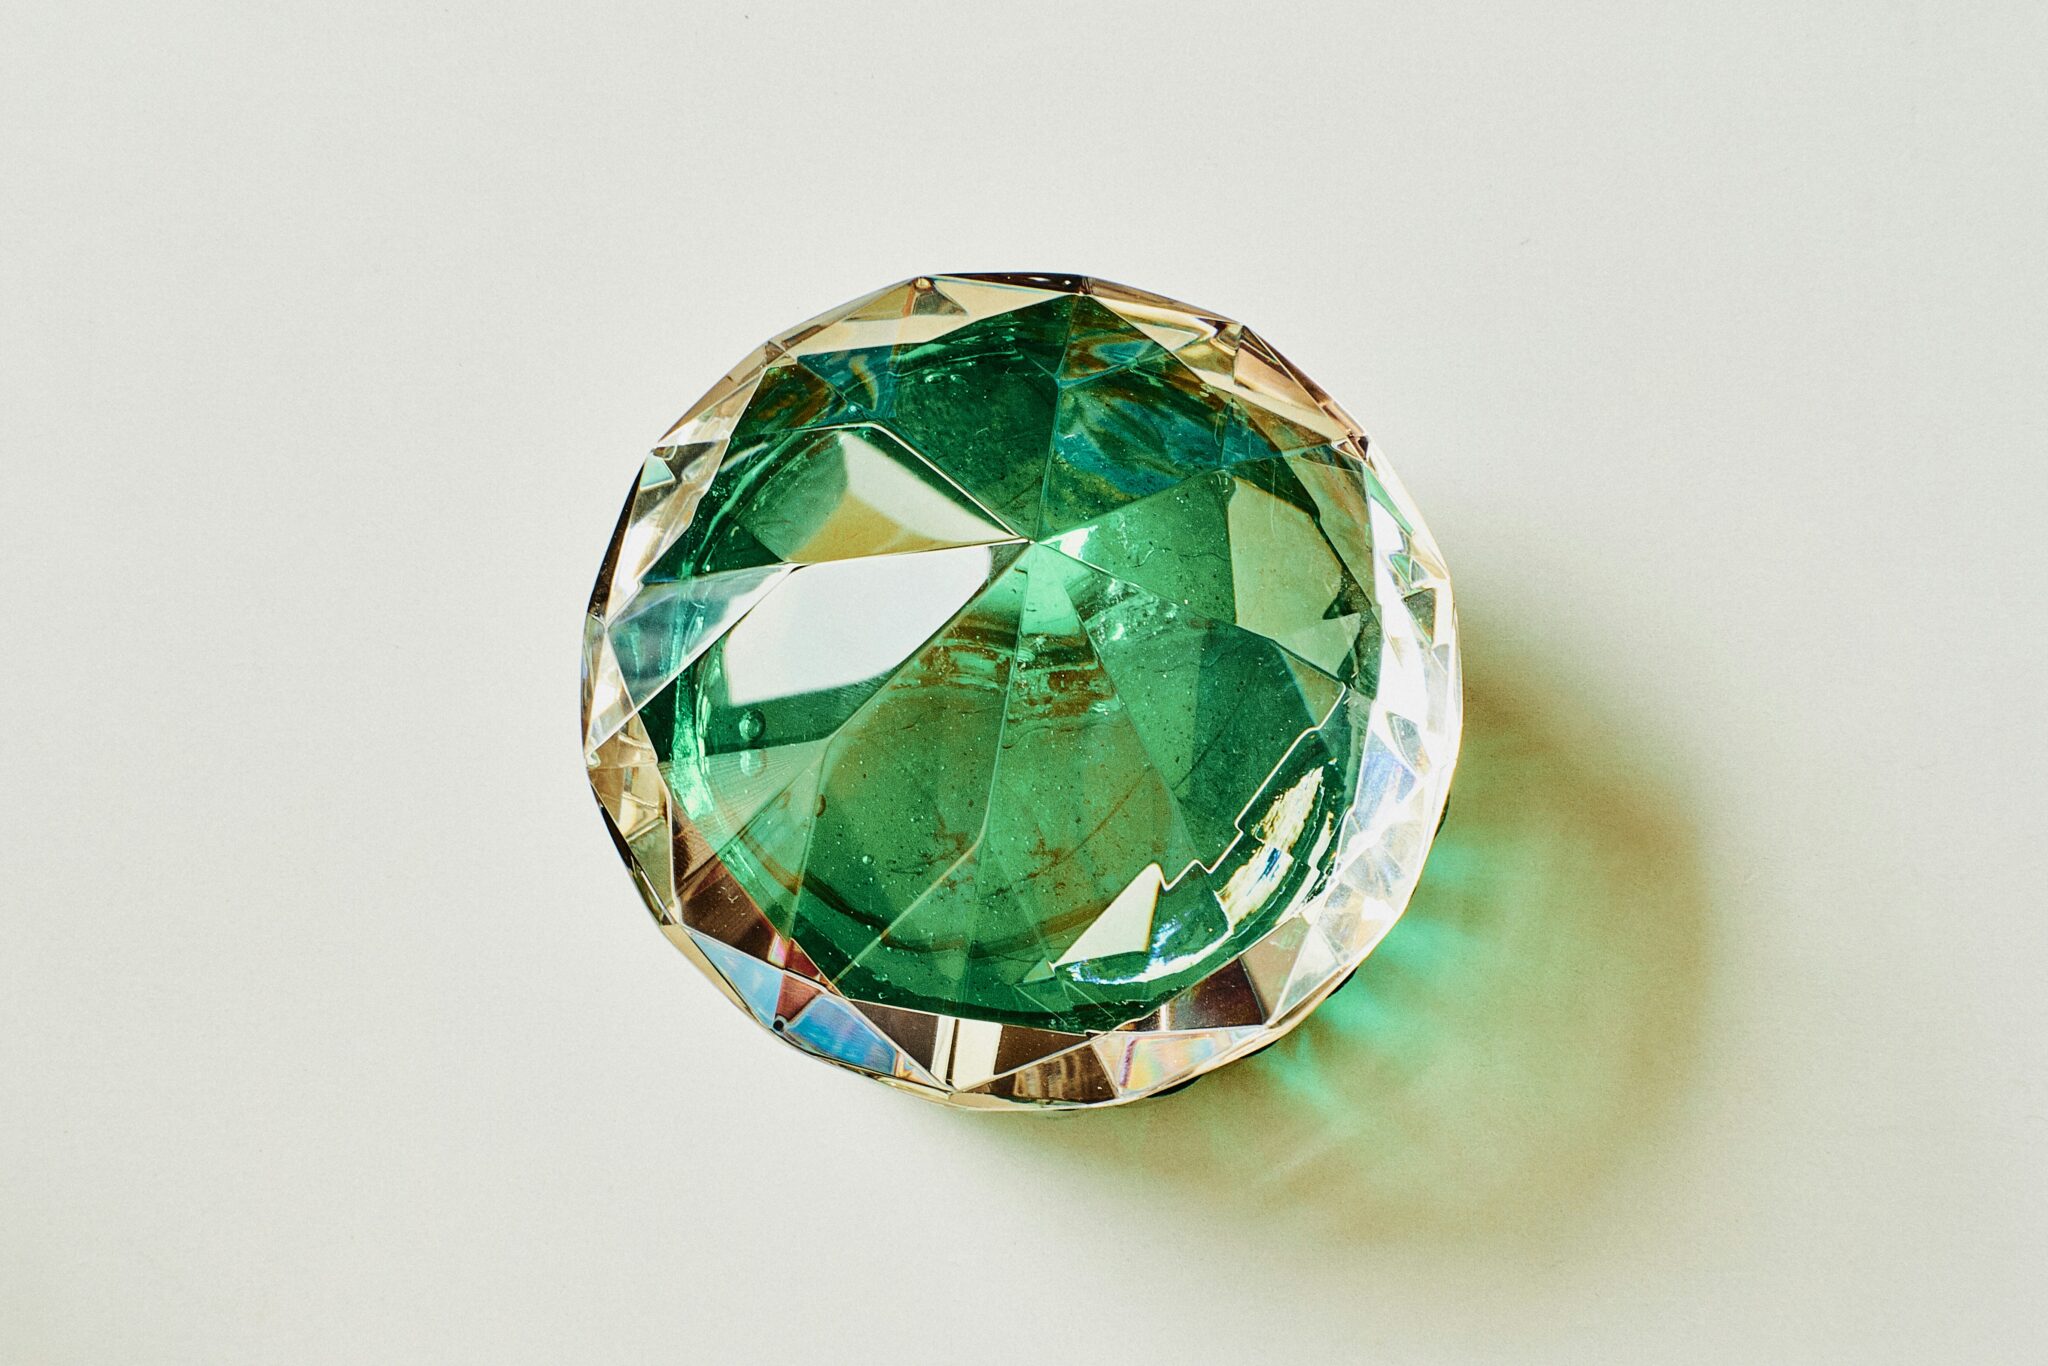
For most of the twentieth century, one company decided how many diamonds the world could buy. At its peak, De Beers controlled around 85% of global rough diamond supply. It didn’t just mine stones. It managed scarcity, released them slowly and kept prices high. Diamonds were never truly rare. De Beers made them rare on purpose.
That system is now collapsing. De Beers’ owner, Anglo American, has written down the business three years running: $1.6bn in 2023, $2.9bn in 2024 and $2.3bn in 2025, a total of $6.8bn. It is now selling its 85% stake in what bne IntelliNews describes as a proposed $1bn deal. In 2012, Anglo paid $5.1bn for just 40% of the company. Few luxury brands have lost so much value so fast, and the story shows how quickly a business built on the psychology of exclusivity can unravel.
Four Words That Built an Empire
In 1947, the New York advertising agency N.W. Ayer handed De Beers four words: “A Diamond Is Forever.”
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeThe line was genius. It persuaded buyers that a diamond was not just jewellery but a symbol of love that should never be sold. That mattered commercially. If nobody resells their diamonds, there is no second-hand market to undercut new stones. The slogan protected De Beers’ prices for generations and became one of the most successful marketing campaigns in history.
It also turned the engagement ring into a social expectation. The idea that a man should spend a large share of his income on a ring was not ancient tradition. It was largely a twentieth-century marketing creation, and De Beers was its author. Like many luxury businesses, from fashion houses to members’ clubs, its real product was meaning, not the object itself.
The Cartel Cracks
De Beers’ grip began to slip long before lab-grown stones arrived. New mines in Russia, Canada and Australia sold outside its control. Competition regulators in Europe and the United States pushed it to abandon its old stockpiling model. By the 2000s, it had become a large miner rather than the market’s gatekeeper.
Then came the real threat: diamonds grown in factories. Lab-grown diamonds are physically and chemically the same as mined ones. For years they were expensive to produce. Now Chinese factories, many in Henan province, can grow gem-quality stones in a matter of weeks, part of the same industrial push behind China’s export surge.
The result has been a price collapse. Wholesale lab-grown prices fell by roughly 74% between 2020 and 2025, according to Edahn Golan Diamond Research. A finished lab stone now costs 80% to 90% less than a mined equivalent. More than 45% of American engagement ring purchases are now lab-grown.
De Beers’ Own Gamble Failed
De Beers tried to fight on both fronts. In 2018 it launched Lightbox, its own brand of cheap lab-grown jewellery, partly to show that synthetic stones were fashion items, not treasures. The idea was to separate the two markets. It didn’t work. Lightbox closed in 2025, and lab-grown prices kept falling.
Meanwhile, the natural market weakened too. Demand from China, once the industry’s great growth engine, faded as its economy slowed and its consumers stopped spending. Anglo chief executive Duncan Wanblad admitted earlier this year that “there is at the moment a plentiful supply of rough diamonds in the market”. De Beers posted an underlying loss of $511m in 2025, and Anglo cut its carrying value to $2.3bn, as Mining.com reported.
Who Buys a Fallen Giant?
Anglo put De Beers up for sale in May 2024. In July, it chose the Global Diamond Consortium, led by former De Beers chief executive Gareth Penny, as its preferred bidder, according to Reuters via CNBC Africa.
The deal depends on Botswana. The country already owns 15% of De Beers, holds pre-emptive rights and supplies about 70% of its rough diamonds. It wants a bigger say. Angola and Namibia may join the consortium. Botswana’s minister Moeti Mohwasa says the sale should close in the final quarter of this year, and stressed the need for “an experienced operator backed by a stable, long-term ownership structure”. Botswana is courting buyers abroad too: its president was in Beijing this week, opening a Chow Tai Fook boutique.
For Botswana, this is not just a deal. Diamonds are the backbone of its economy. A weaker De Beers means weaker public finances.
Can Natural Diamonds Be Saved?
De Beers’ answer is to sell rarity and origin rather than sparkle. Its recent campaigns, such as its bridal campaign for desert diamonds, stress natural stones formed over billions of years and traced back to the mine. The pitch is that a natural diamond is a piece of history, while a lab stone is a product.
It may work at the very top of the market, where buyers pay for story and provenance. But the mass market, the engagement rings bought by ordinary couples, is moving to lab-grown, and it is unlikely to come back.
Where This Goes
De Beers is a warning for every business built on controlled scarcity. Its power never came from geology. It came from controlling supply and controlling the story. Technology broke the first, and a younger generation of buyers has stopped believing the second.
The new owners will inherit a smaller, more honest business: a miner of genuinely rare natural stones, sold to the wealthy as heirlooms. That can still be profitable. But the empire that persuaded the world a diamond is forever is gone, and at around $1bn for 85%, its new owners are buying a brand at a fraction of its former price.
Related Analysis