

London, 18 October 2026 — EBM Weekend Read — By Brad Adams
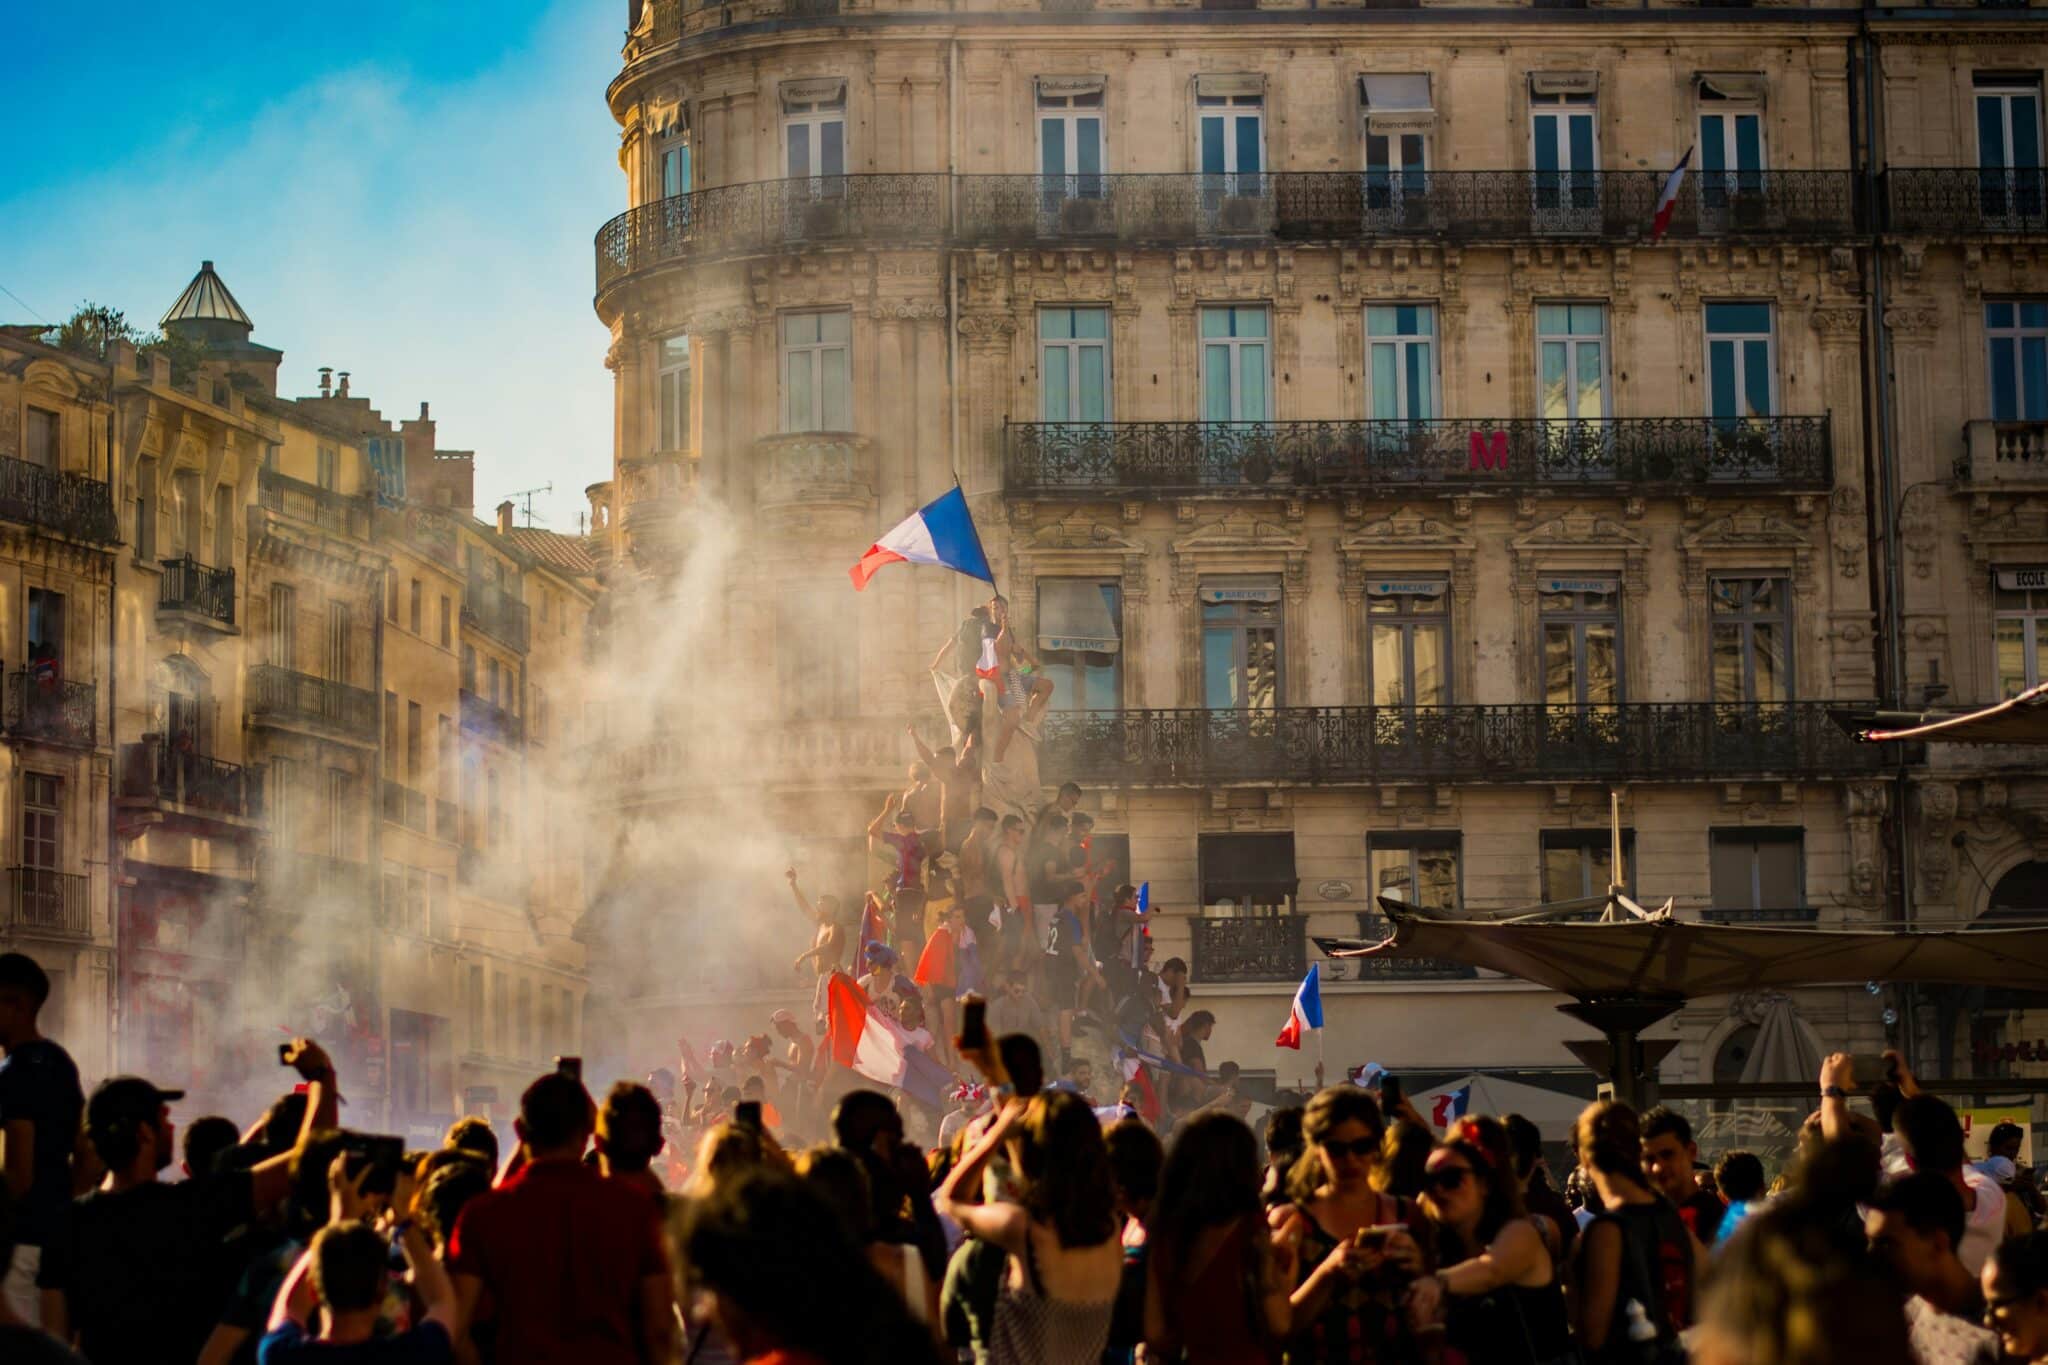
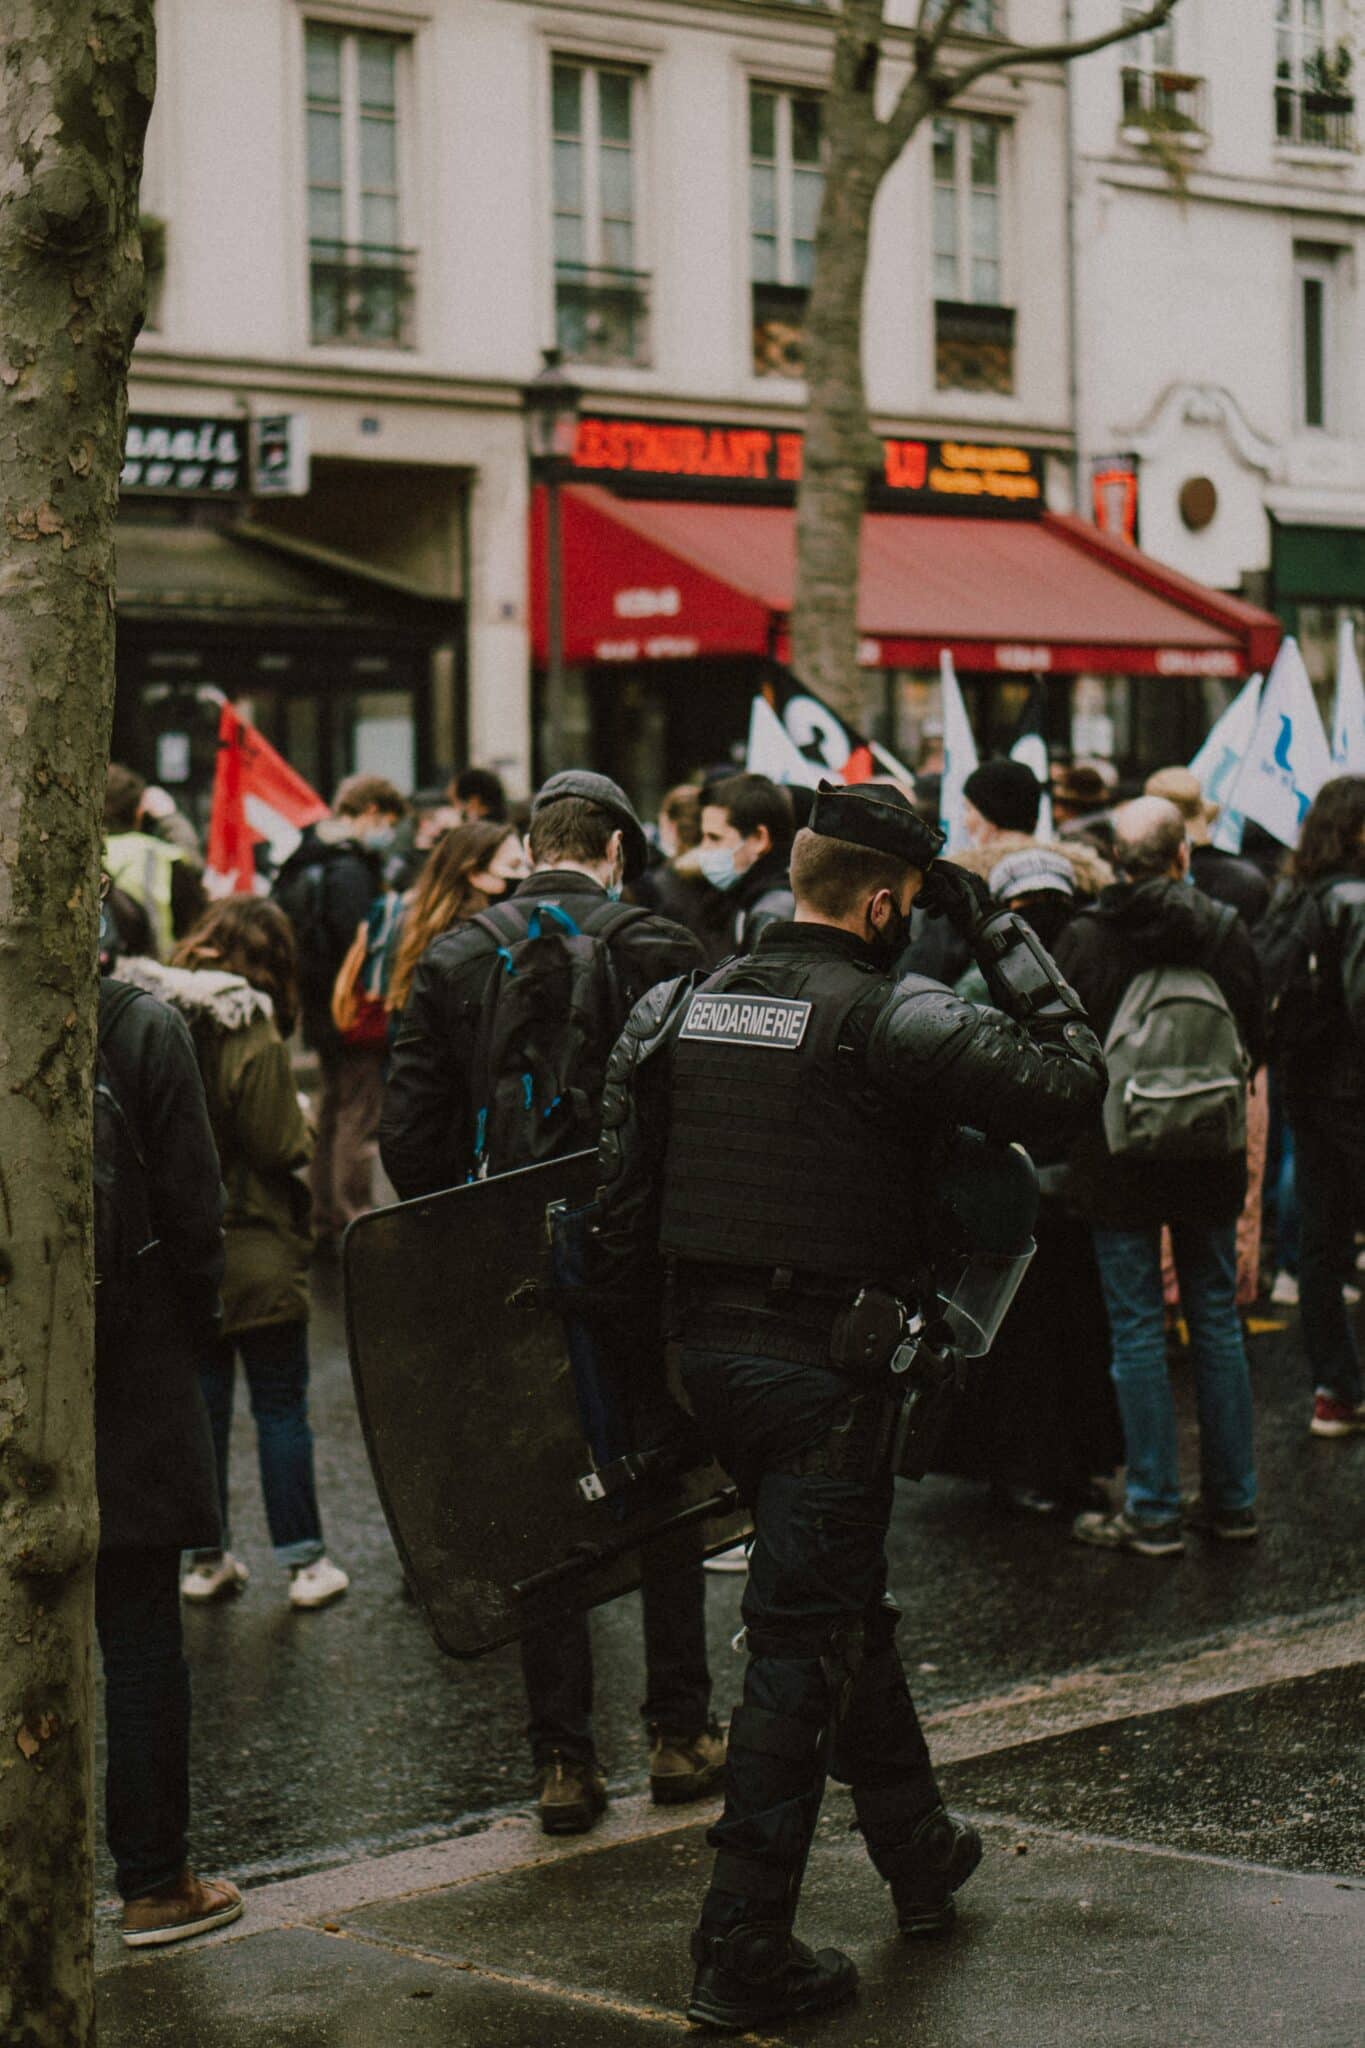
It began in September at a single high school in Créteil, south-east of Paris, where students walked out over crumbling buildings, overcrowded classrooms and missing teachers. By Saturday, 550,000 people were on the streets of France. Shops were looted in Marseille, a tourist office burned in Lyon, and police fired tear gas in Paris. The same day, riot police used water cannon in Brussels and Milan, and tens of thousands marched in Lisbon.
The protests are about schools, fuel and the cost of living. But for investors, the bigger story is in the bond market. France now pays more to borrow than Italy or Greece, and the question in every trading room is whether its crisis stays French or becomes European. It is a fear that has been building since France overtook Italy as Europe’s biggest bond market risk in August.
Why France Matters More Than Greece Ever Did
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeInvestors have noticed. Earlier this month, the extra yield France pays over Germany on 10-year bonds reached 152 basis points, the widest since the 2011–12 euro crisis, as Euronews reported. The 10-year yield touched 5%, its highest since 2002. Our Newsdesk tracked that gap widening through September, and Vanguard has already flagged France as a degrading credit.
A country that size cannot be rescued the way Greece was. That is exactly why it worries everyone else.
The Contagion Channels
Trouble in Paris reaches the rest of Europe in three ways.
The first is through other bond markets. When investors sell French debt, they tend to sell the weaker eurozone borrowers too. During the French turmoil this month, Italian and Greek spreads widened by almost 15 basis points, according to ING. Evercore has warned of a “looming fiscal crisis that could undermine the European Union’s legal framework.”
The second is through the euro. The single currency has already fallen to a 17-month low on French budget fears, and analysts at Intesa think it could slide towards $1.10. A weaker euro raises the cost of imported energy at the worst possible moment, with oil still lifted by the crisis in the Strait of Hormuz.
The third is through banks and pension funds, which hold large amounts of French government debt. When those bonds fall in value, balance sheets across the continent take the hit.
The Same Anger, Different Countries
The protests themselves are spreading too, though they are not one movement. In Belgium, students are protesting against university fees. In Italy, a march against war and living costs turned violent in Milan, emptying Piazza del Duomo. Prime Minister Giorgia Meloni said: “Demonstrating is a right. Setting our cities ablaze is not.” In Portugal, the CGTP union led a march over wages and housing in Lisbon, where house prices have more than doubled since 2017, a pattern familiar from Europe’s wider housing crisis.
What links them is money. Energy and housing costs have squeezed households, while governments carrying heavy debts have little left to help. The global bond sell-off means every new euro of borrowing costs more. The IMF has told rich countries to cut deficits, which is the opposite of what protesters want.
Can the ECB Save France?
In theory, yes. The European Central Bank has a tool called the Transmission Protection Instrument, built to stop bond markets punishing a country unfairly. But it comes with conditions. A country must be following EU fiscal rules and have sustainable debts, and France meets neither test today.
That leaves the ECB in a bind, as we argued when we called France the eurozone’s weakest link. If it steps in too soon, it rewards Paris for failing to fix its finances. If it waits too long, the panic could spread. Macquarie’s Thierry Wizman expects the bank to hold back because of “moral hazard” concerns.
Politics makes it harder. Prime Minister Sébastien Lecornu runs a minority government, and his budget faces a critical vote in the National Assembly on Tuesday. Marine Le Pen, who leads the polls for next May’s presidential election, wants to cut the retirement age to 62. Jean-Luc Mélenchon has floated asking the central bank to cancel the French debt it holds. Neither prospect reassures lenders.
Where This Goes
This is not 2011 yet. The euro has stronger defences than it did then, and France is not Greece. But Europe now faces a dangerous loop. Households protest because life is too expensive. Governments cannot spend to help because markets will punish them. And every sign of unrest makes those markets more nervous.
Tuesday’s vote matters well beyond Paris. If the budget passes, France buys time until the election. If it fails, I expect spreads to widen sharply, Italy to follow, and the ECB to face the test it has spent a decade hoping to avoid. Europe’s governments should be watching the streets of Milan and Lisbon closely. The anger is already there. All it needs is a spark.
Related Analysis