

London, 23 October 2026 — EBM Newsdesk Analysis — By Anthony Gill
Markets are ending a volatile week on edge. Oil has climbed back to its highest level since May, a tech sell-off has shaken confidence, and the worsening situation in the Middle East is keeping inflation fears high. The FTSE 100 struggled to stay in positive territory in early trading. Higher crude prices lifted energy giants, but the wider mood is cautious.
Oil Back at May Highs
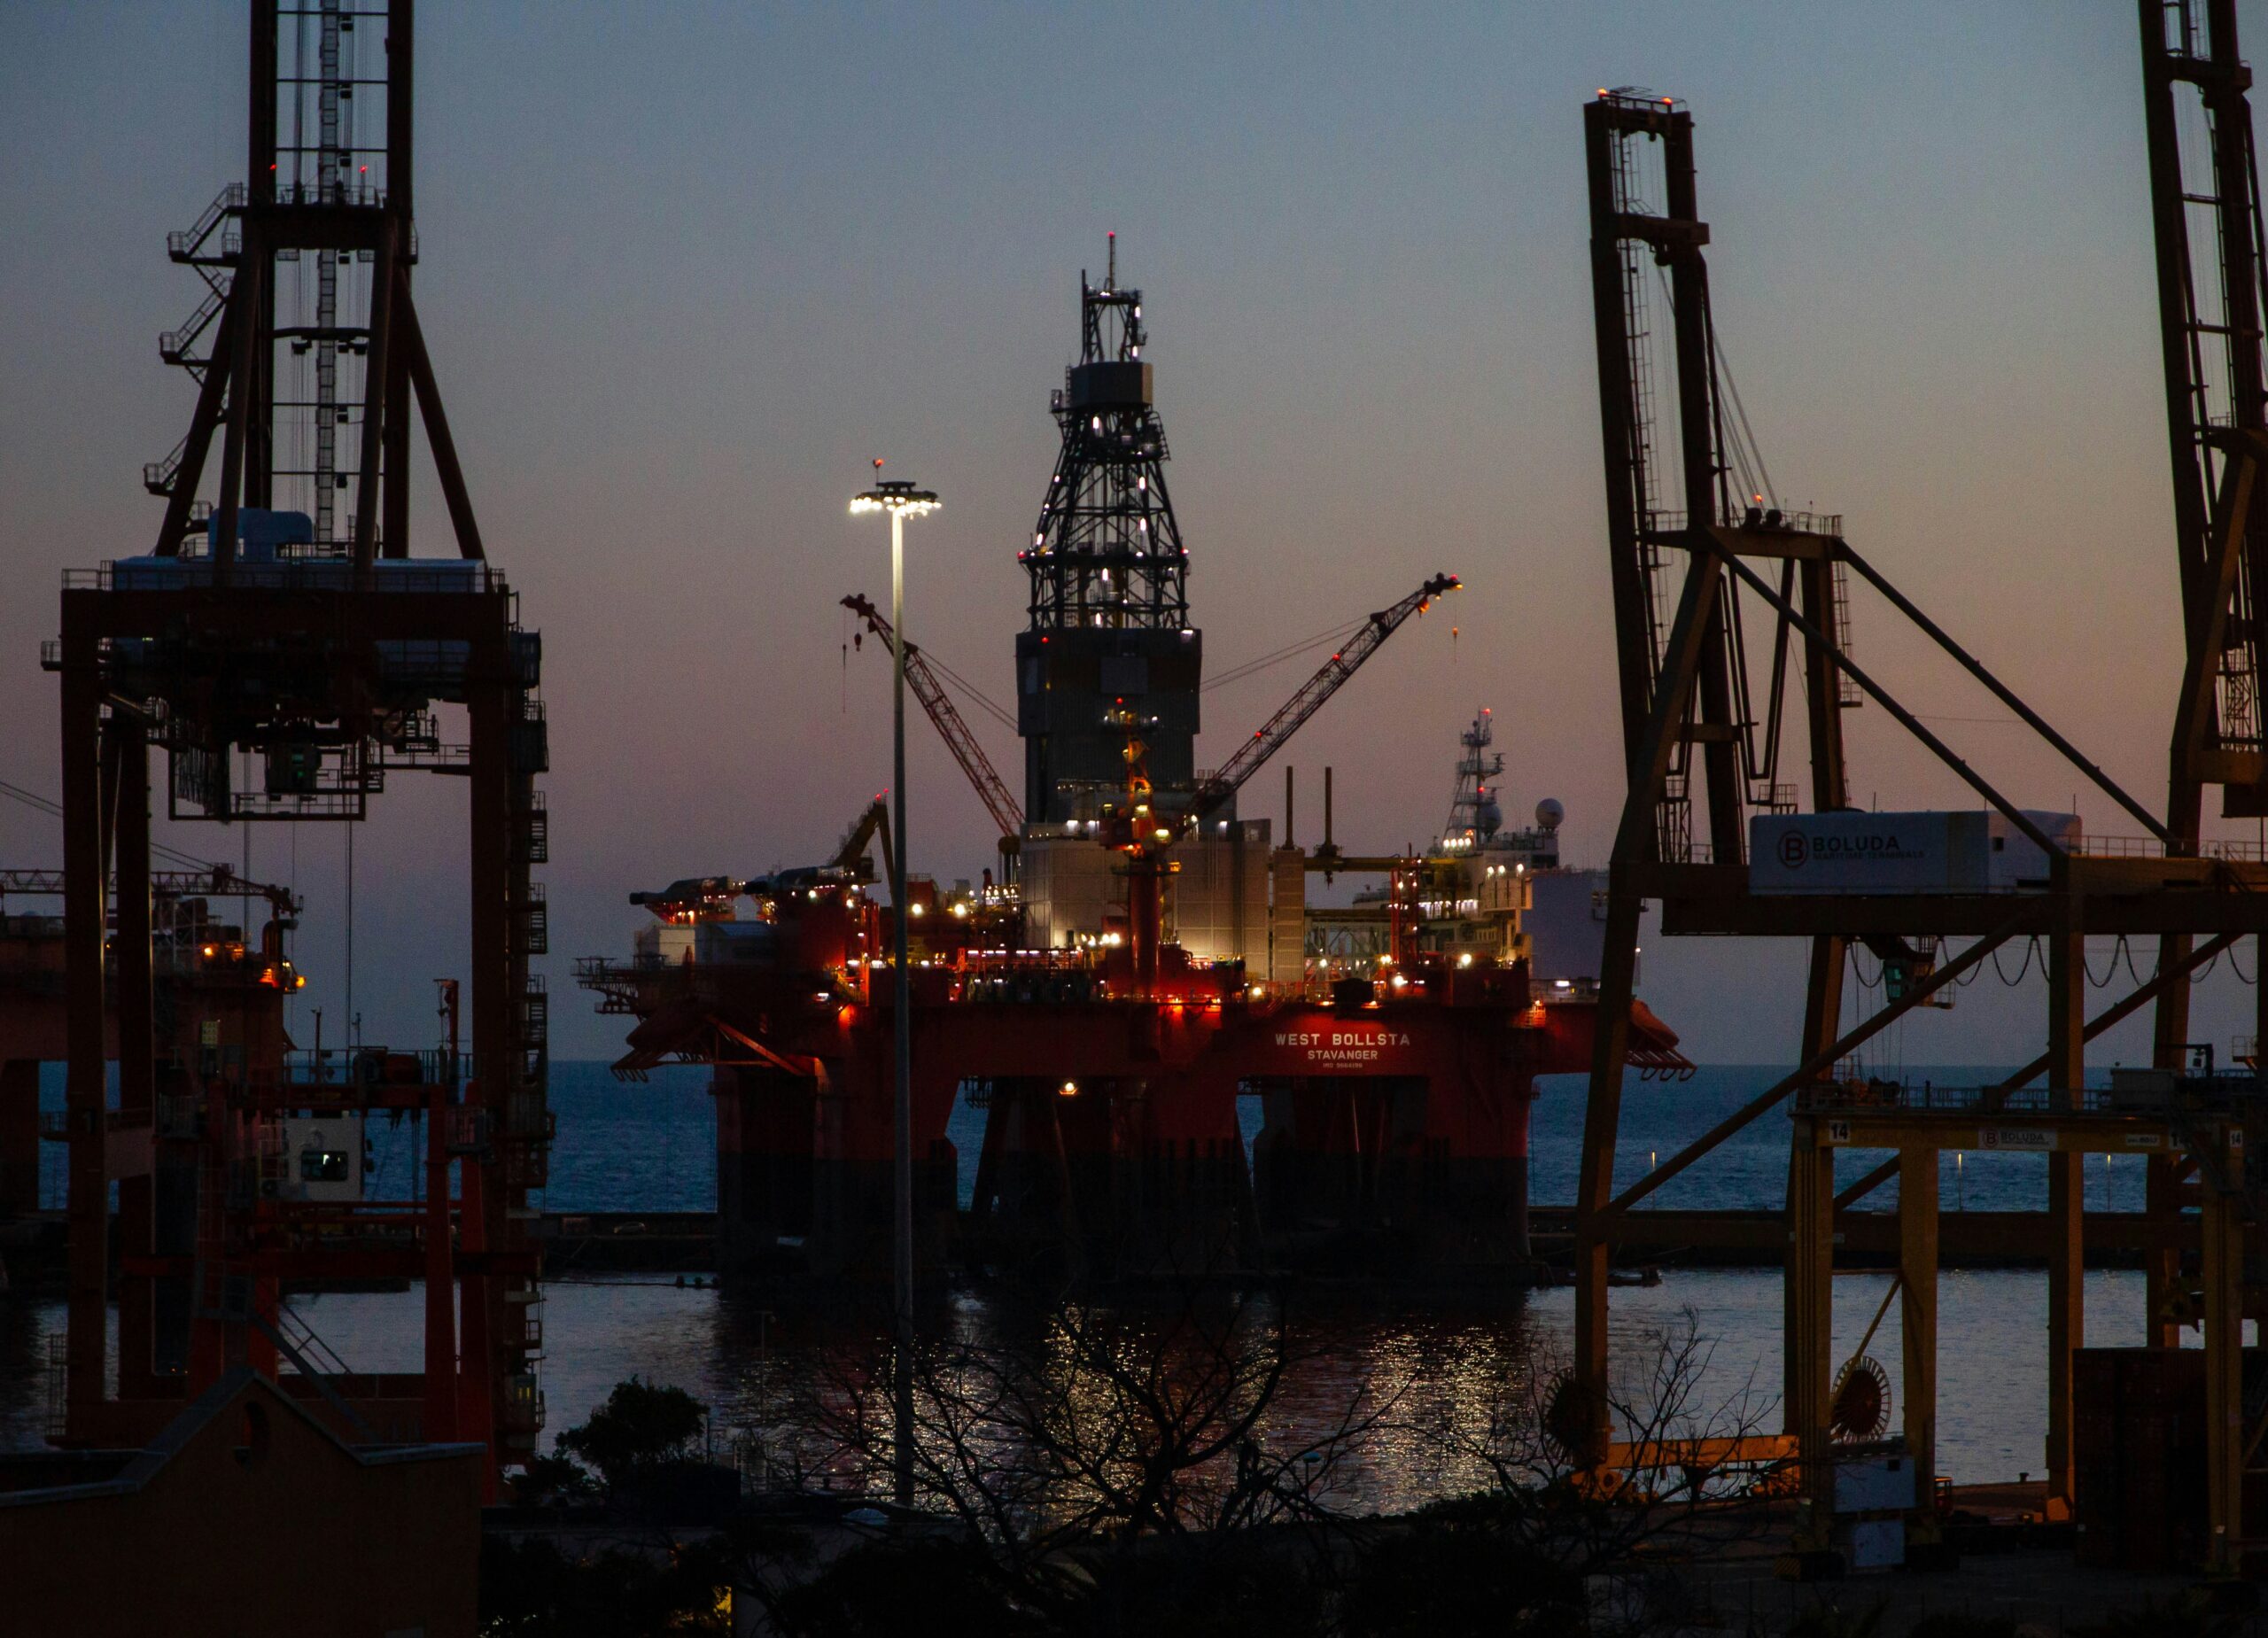
Brent crude has hit $114 a barrel. Fears are growing that American and Israeli forces could strike Iran’s energy infrastructure after the US mid-term elections, with plans reportedly being drawn up.
Houthi attacks on Saudi energy facilities have intensified this week, and ships crossing the Strait of Hormuz still face missile fire. Ukraine’s bombardment of Russian refineries, which has already forced Moscow to ban diesel exports, is adding to supply worries.
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeThe longer these conflicts last, the more likely higher prices become embedded across the economy. Companies cannot keep absorbing rising energy and freight costs indefinitely. That is why markets have increased their bets on faster rate rises from central banks.
Shoppers Close Their Wallets
The damage is already showing up in consumer spending. In Britain, the summer recovery in retail sales is over. Sales volumes fell 0.4% in September, according to the Office for National Statistics. That was a much sharper fall than expected. Households are cutting back on non-essentials, hitting clothing, footwear and homeware hardest.
Unseasonably warm weather made new autumn and winter ranges hard to sell, but the deeper problem is confidence. High fuel prices are hurting, consumers are bracing for painful energy bills, and with UK inflation climbing to 3.5%, many are nervously watching the prospect of rate rises.
That is bad news for the “golden quarter”, the run-up to Christmas on which many retailers depend for their annual profits. Expect heavy discounting as shops try to draw shoppers onto the high street and boost online orders. That will protect sales at the cost of margins.
Tech Takes the Strain
Rising borrowing costs make capital more expensive, and that is sharpening scrutiny of the vast sums being spent on AI. Investors are increasingly nervous about the cost of the build-out, as Meta’s $145bn AI bill showed earlier this week.
The Nasdaq Composite fell 2.6% to 26,009 on Thursday, and the S&P 500 dropped 1.2%. Futures point to a muted start for Wall Street, with little sign of a meaningful rebound. It extends a punishing run for the sector as the AI trade unwinds.
The pressure is not limited to tech stocks. Companies are already using AI to cut costs, as Barclays’ 5,000 job cuts showed this week. That in turn feeds back into weaker consumer confidence.
The Call
Oil is now driving everything. It is pushing up inflation, forcing central banks towards faster rate rises, squeezing consumers and making the AI boom more expensive to fund. Markets can absorb one of those pressures, but not all of them at once. The key date is the US mid-terms. If Washington strikes Iran’s energy facilities afterwards, $114 could quickly become $130, and central banks will have little choice but to keep tightening. Expect a Christmas of deep discounts and thin margins for retailers, and a long winter for tech investors.
Related Analysis