


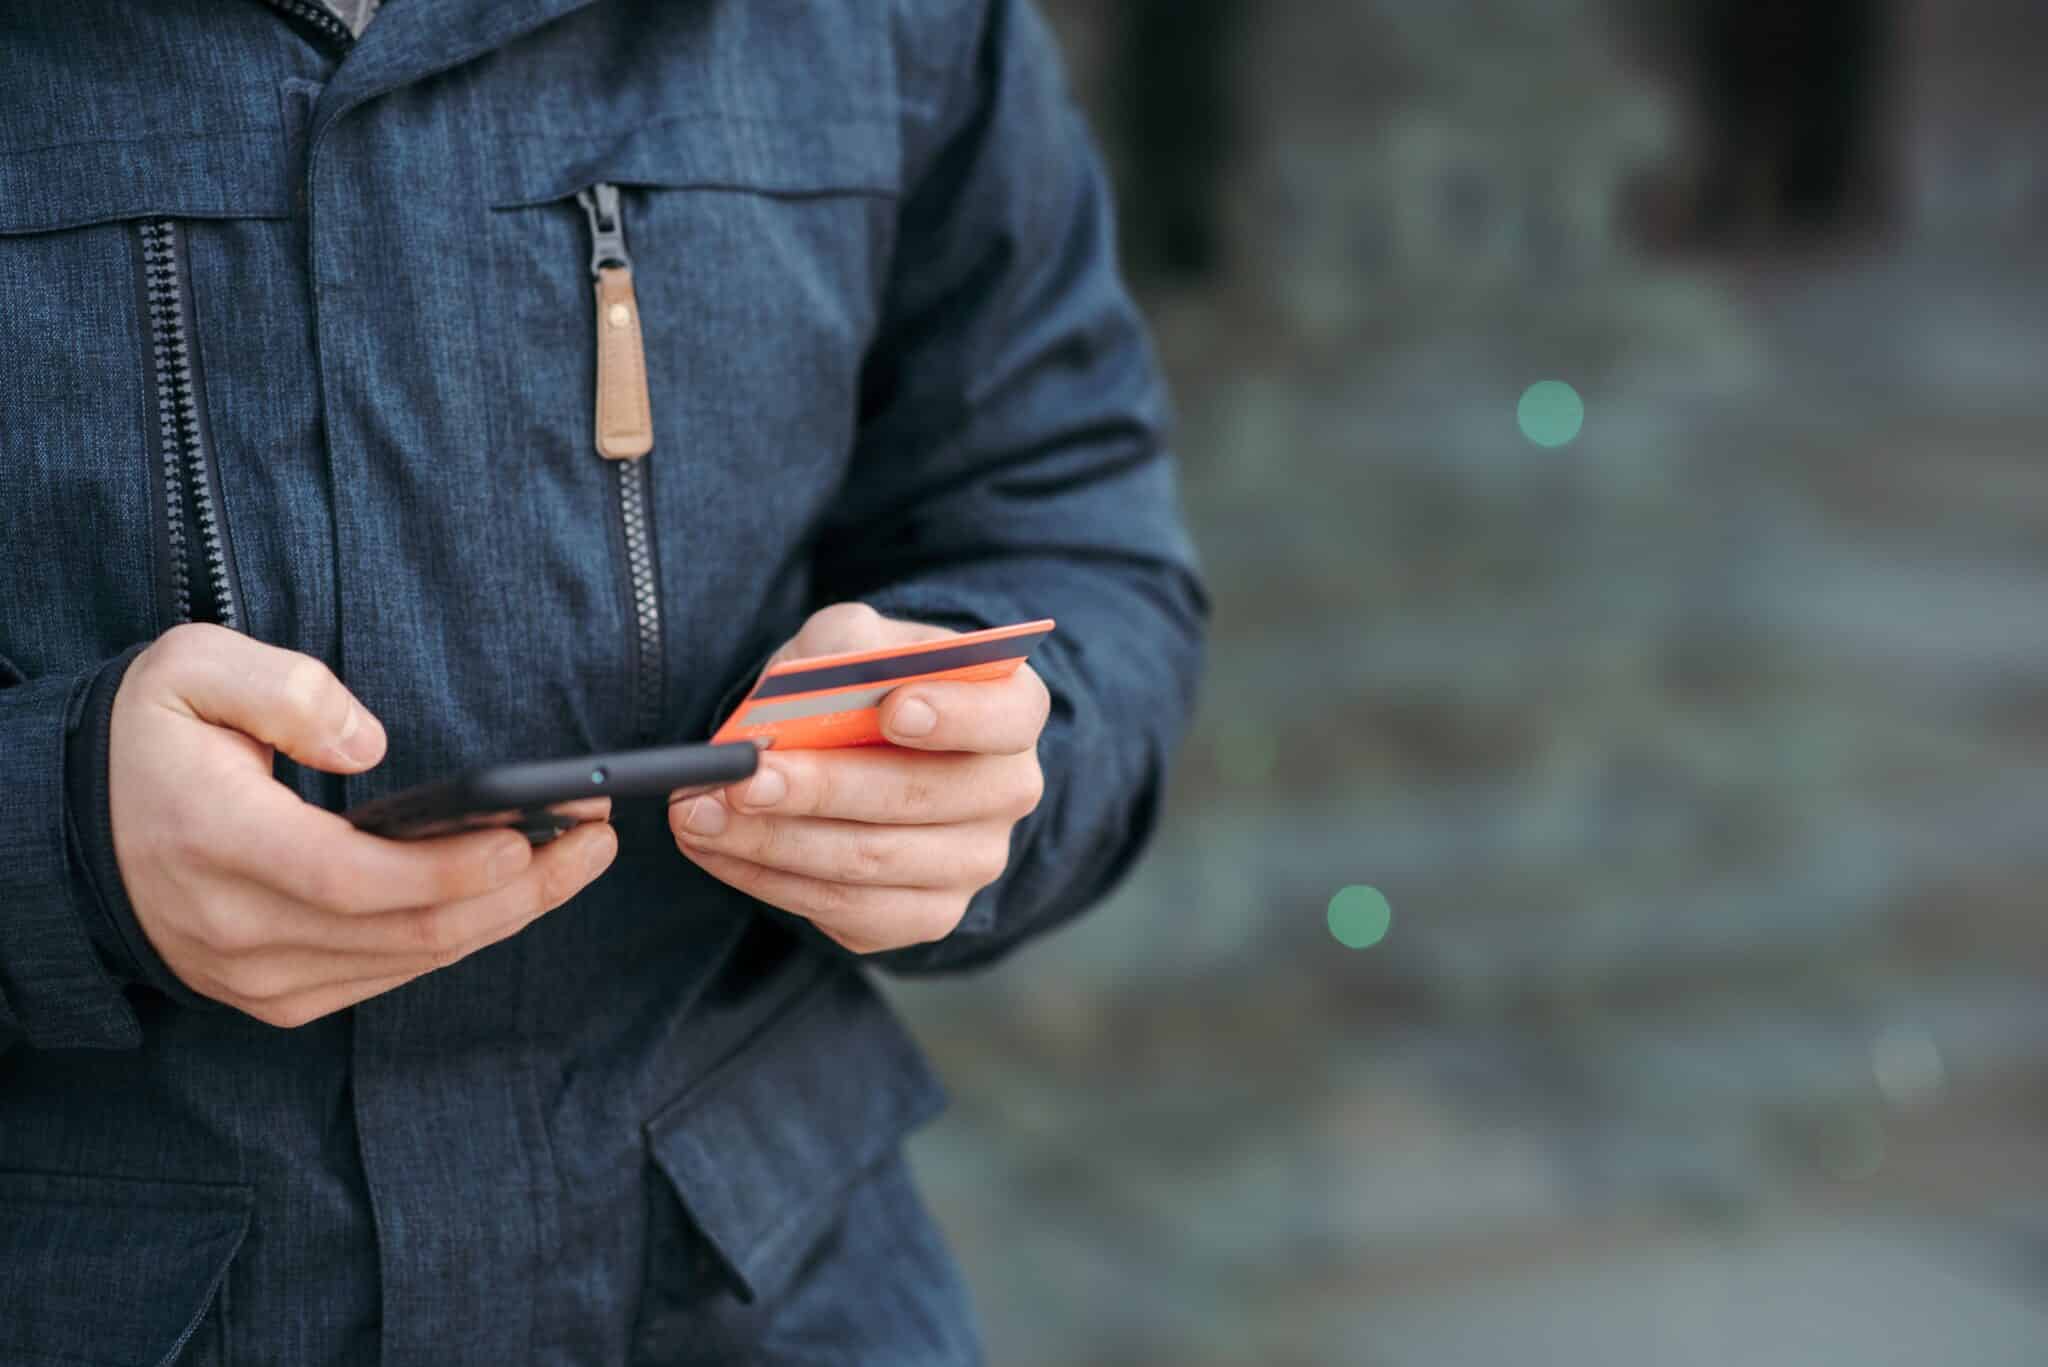
Across the bustling commercial hubs of London, Berlin, and Paris, 260 million mobile banking users interact with their financial portfolios every day. This massive digital shift reflects a profound transformation in how European consumers monitor spending, evaluate purchases, and manage day-to-day liquidity. Gone are the paper ledger books and delayed monthly bank statements of previous decades.
Instead, real-time data integration and digital wallet flexibility have turned everyday smartphones into sophisticated financial command centres. Consumers now demand instant visibility over their purchasing power, compelling traditional financial institutions to overhaul their digital infrastructure. These technological advancements set a new baseline for personal accountability across all major European demographics.
The Shift Toward Digital Spending Transparency
European consumers are no longer willing to wait for end-of-month statements to understand their financial standing. Real-time transaction tracking, instant push notifications, and automated categorisation give individuals immediate context on every euro leaving their accounts. This immediate feedback loop creates a powerful psychological anchor for disciplined budgeting.
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeThis transparency fundamentally alters consumer psychology, making discretionary spending feel far more tangible and immediate. When every coffee purchase or online order triggers an instant visual update on a phone screen, buyers develop a sharper, more acute awareness of their overall cash flow. Such clarity helps households navigate inflationary pressures with greater confidence.
Financial institutions and emerging technology platforms have responded by integrating advanced software tools that predict upcoming subscription renewals and flag unusual account activity. These automated oversight layers significantly reduce cognitive load for everyday users who juggle complex webs of utility bills, rent payments, and digital entertainment subscriptions.
Rather than guessing available account balances or mentally calculating monthly budgets, consumers operate with absolute precision and clarity. This heightened financial visibility naturally leads people to evaluate their purchasing habits long before they reach physical checkout lines or online cart confirmations.
How Mobile Apps Shape Purchase Decisions
Modern finance applications do much more than simply display static numerical balances; they actively reshape consumer behaviour through thoughtful behavioural design and targeted spending insights. Mobile platforms leverage sophisticated data visualisation to break down monthly expenditures into digestible categories like dining, public transport, and leisure. Users can easily spot outlier expenses before they derail long term savings objectives.
When users see their discretionary funds dwindling midway through the month, psychological friction enters the shopping process. Here are the primary ways these digital tools influence everyday consumer behaviour:
- highlighting recurring subscription costs that often go unnoticed
- providing visual progress bars for short-term savings goals
- flagging spending spikes relative to historical monthly averages
These interactive mechanisms encourage people to pause, reflect, and evaluate their financial priorities before completing a transaction. Platforms like the 118m8.com website exemplify this consumer-focused approach by helping users recognise emerging spending patterns and pause before making impulsive purchases. By introducing deliberate pauses into the user journey, these applications transform passive buyers into mindful financial decision-makers, and consumers begin to view their mobile financial dashboard not merely as a record of past transactions, but as a proactive guide for future economic choices.
Overcoming Impulse Buys With Behavioural Friction
Impulse buying has historically thrived on seamless, frictionless checkouts where purchasing an item takes only a single click. Fintech innovators are actively countering this frictionless trap by engineering intentional pauses and evaluation steps into the modern buying workflow. These deliberate design choices restore intentionality to digital retail environments.
When a user contemplates a non-essential purchase, modern budgeting software prompts them to weigh the item against existing savings targets or monthly limits. Financial platforms continue to evolve rapidly as payment technologies integrate real-time consumer protection layers across diverse European markets.
This counter-intuitive friction protects everyday users from buyer’s remorse and fosters long-term financial stability across diverse demographic groups. European consumers are increasingly embracing these digital guardrails as living costs fluctuate across different economic regions.
According to recent global payments report data, digital transactions continue to capture a dominant share of consumer retail activity throughout the continent. This widespread adoption means that digital intervention tools reach a massive audience of everyday shoppers who need practical support in managing their budgets.
As these features become standard across mobile banking ecosystems, financial wellness shifts smoothly from an elusive personal goal into an effortless everyday habit. Modern financial habits require continuous reinforcement through accessible digital tools that empower users at every step of their journey.
Building Sustainable Financial Habits Across Europe
The rapid maturation of Europe’s digital finance landscape shows that modern technology can bridge the gap between payment convenience and rigorous financial discipline. Consumers no longer have to choose between swift digital transactions and mindful money management.
As mobile applications continue to refine their insight engines and behavioural prompts, European shoppers gain deeper, more resilient control over their economic futures. Navigating the modern economic landscape requires tools that adapt to individual spending behaviours while encouraging long-term prudence. For further exploration of digital spending trends and financial psychology across Europe, check out the insights covered on our blog.