


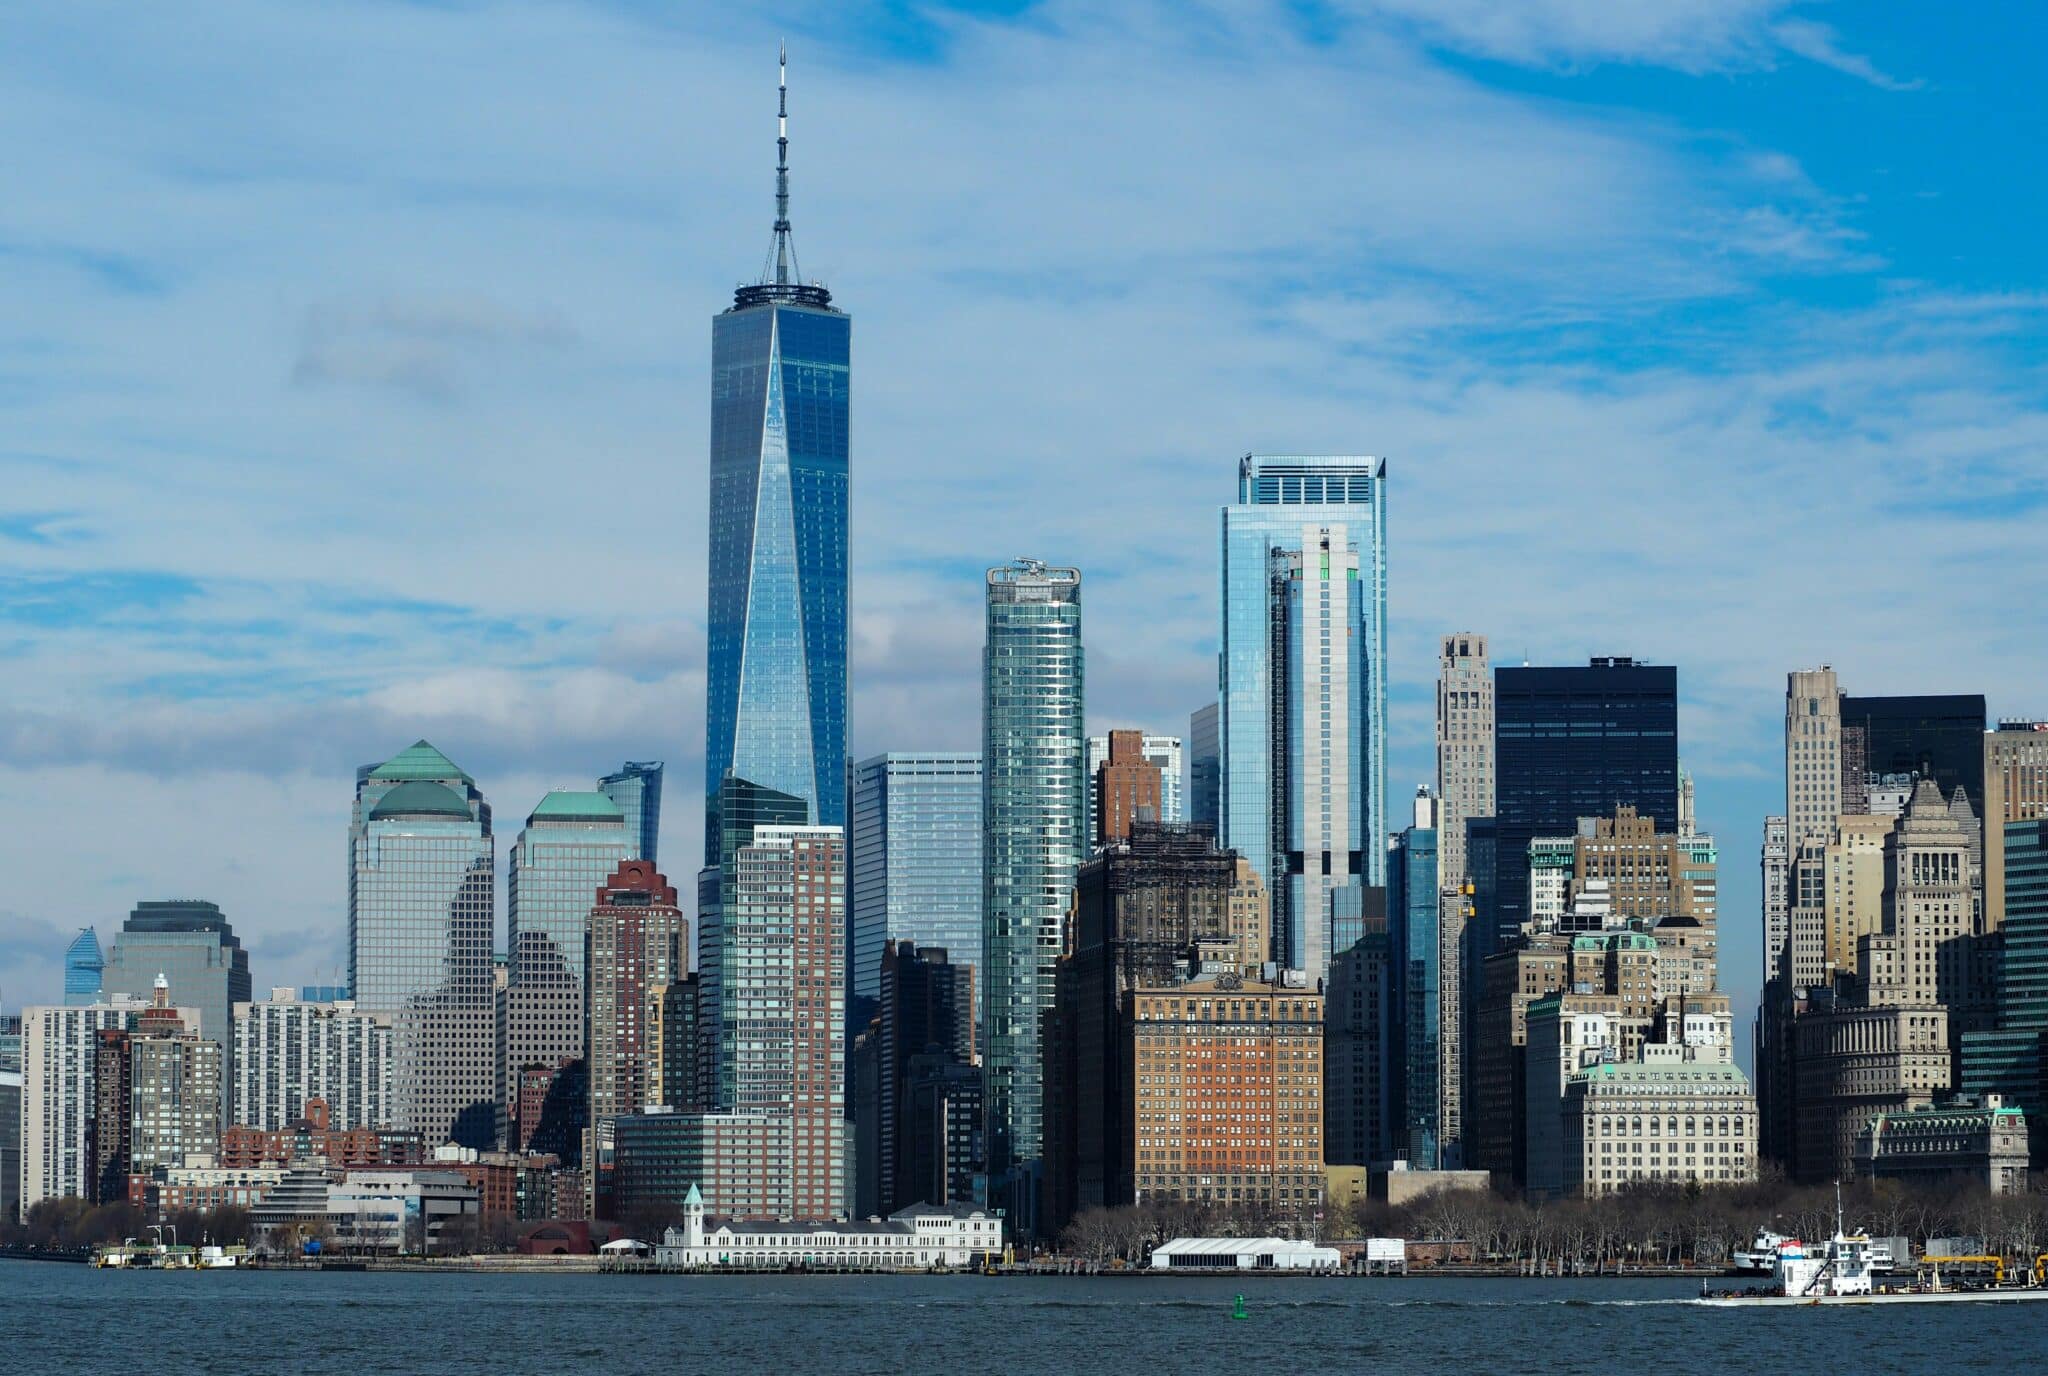
Operating in Manhattan means navigating a dense regulatory environment where city, state, and federal requirements intersect. For small and medium enterprises, maintaining compliance is not just a legal obligation but a competitive advantage that supports financing opportunities, vendor relationships, and client trust. The right blend of internal processes, external expertise, and technology can reduce the risk of penalties and free leadership to focus on growth.
Understand the local tax landscape
Join The European Business Briefing
New subscribers this quarter are entered into a draw to win a Rolex Submariner. Join 40,000+ founders, investors and executives who read EBM every day.
SubscribeManhattan businesses must account for New York State income tax, New York City business taxes where applicable, and various industry-specific levies. Sales tax collection and remittance can be especially complex for retailers and service providers operating across multiple boroughs or selling online. Regularly reviewing tax jurisdictions for physical presence, nexus, and economic activity thresholds will prevent surprising liabilities. Engage with updated guidance from the New York State Department of Taxation and Finance and the NYC Department of Finance, and schedule quarterly reviews of tax positions so adjustments are timely rather than reactive.
Strengthen internal controls
Internal controls are the first line of defense against misstatements and fraud. Segregation of duties, even in small teams, can be achieved through role clarity and periodic cross-checks. Implement approval limits that require secondary sign-off for significant disbursements and vendor onboarding. Reconcile bank accounts and payroll monthly rather than quarterly to catch anomalies early. A culture that encourages questions about unusual transactions will complement procedural safeguards by ensuring staff understand that compliance is an operational priority rather than a box-checking exercise.
Keep documentation audit-ready
Recordkeeping standards matter when auditors, lenders, or regulators request information. Maintain organized financial records that tie source documents to ledger entries: invoices, contracts, timecards, and reconciliations should be easy to retrieve. Retention policies must balance legal requirements with practical accessibility; for example, many tax-related documents should be retained for at least seven years. When a review or audit occurs, being able to present a complete paper trail demonstrates credibility and often shortens the review period.
Leverage technology for accuracy and efficiency
Modern accounting platforms can automate recurring processes such as invoicing, payroll tax calculations, and sales tax collection across multiple jurisdictions. Use software with robust access controls and audit trails to reduce human error and produce reliable reports for compliance checks. Data integration between point-of-sale systems, payroll, and general ledger reduces manual entry and creates a single source of truth. Regularly back up financial data and maintain version control so historic statements can be reconstructed if needed.
Build the right partnerships
Compliance isn’t handled in isolation. Establishing relationships with legal counsel, payroll providers, and trusted accounting advisors helps translate regulation into practical procedures. Smaller firms benefit from outside expertise during filing season, when new tax rules appear, or when entering complex transactions such as leases or equity financing. When selecting external advisors, choose professionals who understand Manhattan’s market dynamics and regulatory nuances; for many businesses, working with an accounting firm in New York brings local knowledge that complements internal teams.
Prioritize payroll and employee-related obligations
Payroll is a frequent source of compliance issues. Accurately applying withholding rates, handling benefit deductions, and meeting timely deposits are essential to avoid penalties and employee dissatisfaction. New York City also has specific regulations regarding paid family leave and local wage ordinances that require careful calculation and transparent communication. Maintain detailed payroll records and perform reconciliation of payroll liabilities to bank activity monthly to ensure payroll-related taxes and contributions are remitted correctly.
Monitor vendor and contract compliance
Contracts often carry compliance obligations that extend beyond payment terms—insurance requirements, certification renewals, and regulatory reporting clauses can create downstream risk. Establish a vendor management process that tracks expiration dates, insurance evidence, and any audit rights contained in agreements. For construction, hospitality, and professional services, licensing and permitting are crucial; centralize these records and set automated reminders to prevent inadvertent lapse.
Prepare for audits and regulatory inquiries
Regulatory scrutiny can arrive unexpectedly. Preparation reduces stress and exposure. Create an internal audit calendar that evaluates high-risk areas like revenue recognition, expense classification, and government filings. Conduct mock audits to train personnel on document retrieval and to identify gaps before a third-party examiner arrives. If regulators request information, provide timely, accurate responses and consult counsel for complex questions; transparency and cooperation often mitigate penalties.
Continuous training and risk management
Regulatory requirements evolve, and employee turnover can erode institutional compliance knowledge. Establish an ongoing training program for finance, operations, and front-line staff to ensure everyone understands their responsibilities. Combine annual formal training with brief, situational refreshers tied to policy changes or common error types. Finally, treat compliance as part of enterprise risk management: evaluate the likelihood and impact of failures, allocate resources to the highest risks, and revisit the plan whenever the business expands, changes service lines, or pursues new markets.
Compliance in Manhattan requires diligence, local insight, and a commitment to process. By integrating strong internal controls, leveraging technology, keeping detailed records, and partnering with experienced advisors, businesses can reduce regulatory friction and focus on long-term objectives. Sound compliance is not merely defensive; it creates operational transparency that supports financing, growth, and reputation in one of the world’s most dynamic markets.